YBF #FinTech pitch night

It’s getting difficult to keep up with all the FinTech activity in Melbourne – from Meetups to pitch nights, from hubs to incubators. The latest Next Money / York Butter Factory / Fintech Victoria pitch night was a showcase for three startups-in-residence at YBF. As such, it was not the usual pitch competition – more an opportunity for the startups to hone their presentations.
First up was Handy, an app-based solution that connects trades with customers to streamline the settlement process for property insurance claims. There is an industry-wide low-level of satisfaction with property claims – which can take up to 60 days to process, even though 80% of claims are for less than $5,000. Handy offers a faster solution, and doesn’t require a lengthy estimate or quoting process, using instead fixed-price rates. With a target market of 100,000 claims per annum, Handy expects to generate 25% savings to the insurance industry, as well as having a broader societal impact in terms of speedier claims, better appreciation of service providers, and more consideration of the respective needs of householders and trades. Launching an MVP in November, there are four insurance firms in pilot test mode. Aiming for a white label solution, Handy will charge clients basic setup and maintenance fees, as well as volume transaction costs (although the exact pricing and revenue model still needs to be worked out). There were audience questions about the liability for quality of work and dispute resolution, the trade supplier on boarding and verification process, and the process for communicating to policy holders whether their insurance provider or broker is covered by the platform.

Next was FinPass, a startup appealing to the 40% of the workforce expected to be freelance by 2020 – a key feature of the gig economy. Targeting so-called “slashies“, FinPass is designed to help customers apply for personal loans when they don’t have a single, steady or stable source of income – and therefore, may lack a formal credit rating or personal credit score – while adhering to the five Cs of credit. Using a combination of blockchain and API to validate a loan applicant’s income profile, FinPass would then make this data available to approved lenders (subject, presumably, to consumer credit and lending standards, customer privacy and data protection requirements). To be fair, this project was fresh from winning a recent hackathon event, and therefore is still at the concept stage. However, it was clear that much needs to be done to define the revenue model, as well as designing the actual blockchain solution. Audience feedback questioned the need for a standalone solution, given the existence of various block explorers, APIs, vendors, protocols and bank feed sources. In addition, while blockchain provides a level of transaction immutability, and since only the hash-keys will be captured, the SHA’s will only confirm the hash itself, not the veracity of the underlying data?

Finally, there was Resolve, a two-sided market place for the insolvency services – a platform to buy and sell distressed businesses. Designed to capture turnaround opportunities, the platform has a target market of 14,000 transactions per annum – of which only 1% currently advertised, simply because it’s too expensive to use traditional media (i.e., finance and business publications). In addition, 92% of companies that enter insolvency return zero cents in the dollar to their creditors. Part bulletin board, part deal room, Resolve aims to create a passive deal flow for this alternative asset class. When asked about their commercial model, the founders expect a turnover based on a few hundred businesses each year, and revenue coming from a flat $1,000 per listing – but the key to success will be building scale.

Each of these early-stage startups represent promising ideas, revealing some innovative solutions, so it will be interesting to follow their respective journeys over the coming months.

Next week: Bitcoin – Big In Japan
Supersense – Festival of the Ecstatic

Taking a break from startups, FinTech and digital disruption, I spent the past weekend at this year’s Supersense at the Melbourne Arts Centre. This underground festival (both literally and culturally) is back after 2015’s launch event, with an even more ambitious yet also more coherent line-up. It was still an endurance test, and while there were several absorbing performances, in the end it felt like there was nothing that was totally outstanding.

Part of the problem is we are so overloaded with aural stimulation that it takes something truly special to capture our imagination. First, we have access to an endless supply of music (thanks to Apple, Spotify, Bandcamp, Soundcloud, BitTorrent, Vimeo, Resonate, Napster, Vevo, Gnutella, YouTube…). Second, what was once deemed subversive or cutting edge, has now been appropriated by the mainstream and co-opted into the mass media. Third, and as a result of which, when it comes to the avant-garde, there is a sense of “been there, seen that”.

Alternatively, perhaps after more than 40 years of watching live music my palette has become jaded. But I’m also aware that theses days, some of the really interesting and engaging “live” audio experiences are to be found in art gallery installations, site-specific works and interactive pieces. For much of the festival, there was the traditional boundary between performer and audience – even though the idea was to wander between the different performance areas, we were still very much spectators.

A large part of the programme was given over to genre-pushing performances.  But even here I realize that, whether it’s free jazz, improvisation or experimental sounds, there is an orthodoxy at work. Many of these performers are playing a pre-defined musical role, whether it’s torch singer, axe hero, R&B diva, stonking saxophonist, glitch supremo, string scraper, drone aficionado or ur-vocalist.

Some performers played the venue as much as their instruments (stretching the acoustic limits of the building). Some even ended up “playing” the audience (in the sense of stretching their patience and tolerance). And in the many collaborative pieces, the musicians were mainly playing for or against each other, somewhat oblivious to the audience. In such circumstances, the creative tension did provide for some interesting results; but as so often with virtuoso performances, the players that relied only on speed, noise, volume or however many (or few) notes they produced were probably the least interesting.

Overall, few performers offered much variety within their allotted time slots. For all the colour, range and styles on display, many of the individual sets were extremely monochromatic, with little in the way of transition or shade. The volume, tones and textures were always full on. Pieces lacked development, and did not reveal or explore the aural equivalent of negative space. I understand and appreciate the importance of minimalism, repetition and compressed tonality in contemporary composition, but I was also hoping for a more layered approach to these live performances, and even some juxtaposition or contrast.

The subtitle of Supersense is “Festival of the Ecstatic”, with the implication that the audience will be swept away on a (sound) wave of transcendence. When it came to being enraptured, as with so many things these days, less is more. So the key sessions for me included: Oliver Coates who mesmerized with his solo cello performance; Jannah Quill and Fujui Wang whose laptop glitches sounded like a version of Philip Jeck’s “Vinyl Requiem” using only the works of Karlheinz Stockhausen; Zeena Parkins‘ sublime piano drone harmonics; JG Thirwell‘s minimalist sound poem; and Stephen O’Malley’s plaster-shredding guitar feedback oscillation. Whether or not it was the intended effect, during a number of performances I actually found myself drifting into a soporific state of semi-consciousness – but maybe it was just fatigue setting in?

Of course, I am extremely grateful that this type of event exists – it’s essential to have these showcases, for all their limitations and challenges. But it’s a bit like being a tourist: there are lots of destinations we may like to visit, but we wouldn’t want to live there – and there are some places where it’s enough just to know they are there.

Next week: FinTech and the Regulators

Bringing Back Banter

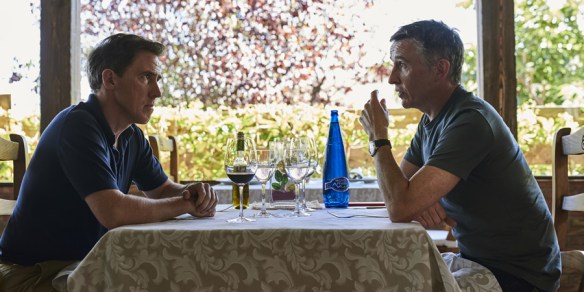
Last week I watched “The Trip To Spain”, the latest in the “Trip” franchise. For anyone who has not yet seen these films (or the TV series from which they are compiled), the narratives revolve around a pair of actors playing fictional versions of themselves, as they embark on road trips to sample some of the best restaurants, hotels and historic locations. The semi-improvised dialogue between the two main characters is classic banter – as in “the playful and friendly exchange of teasing remarks“.

The gentle art of banter is at the heart of “The Trip To Spain” – Image sourced from British Comedy Guide

Sadly, just as the public discourse has become much uglier in recent years (despite various calls for a “kinder, gentler politics”), it seems there is something of a backlash against neo-banter (or “bantaaaaaaah!” as some would have it). Maybe there is a connection?

If our political leaders cannot engage in the natural ebb and flow of an ideological discussion shaped as informed conversation (rather than embarking on all out verbal warfare), then don’t be surprised if this is the same boorish, belligerent and bellicose tone adopted by protagonists in social media, op eds and parliamentary “debates”. (And I am not defending anyone who uses the term “banter” to excuse/explain the inappropriate.)

Banter can help to explore hypothetical scenarios, suggest alternative opinions, and take a discussion in different directions, without participants being hidebound by the first thing they say. Plus, if done really well, it allows us to see the ultimate absurdity of untenable positions.

Next week: Supersense – Festival of the Ecstatic


Bitcoin – to fork or not to fork?

Anyone following the crypto-currency markets this past two weeks will be fully aware that this has been a turbulent time for Bitcoin and other blockchain assets. First, the SEC published its Report on the DAO.  Second, there was a significant arrest in connection with the Mt Gox failure. And third, Bitcoin underwent a fork which has resulted in a new version, known as Bitcoin Cash. Meanwhile, at the time of writing, the price of Bitcoin itself is testing renewed highs, and continues to enjoy a 3-month long rally.

What implications do each of these developments have for the digital asset industry?

Photo by Andre Chinn – Image sourced from Flickr under Creative Commons

The Mt Gox-related arrest came as Japanese authorities began separate criminal proceedings against the former head of the failed exchange. These developments underscore two things: 1) as with any complex financial fraud investigation, bringing the culprits to justice takes time. 2) exploiting the financial system for ill-gotten gain is not exclusive to crypto-currencies – just ask investors in Australia’s CBA bank how they feel about losing nearly 4 per cent of the value of their shares in one day on the back of a money laundering scandal.

It also means that as regulators play catch-up, exchanges, brokers and other participants in the crypto-currency markets will need to ensure that they are updating their security and privacy systems (to prevent future hacks) while ensuring they comply with AML/KYC/CTF provisions. No bad thing, to instil confidence and trust in this emerging asset class, which is entering a new phase of maturity.

The SEC Report on the DAO, meanwhile, has put ICO’s (Initial Coin Offering) and TGE’s (Token Generation Event) on notice that in some cases, these products will be treated as securities, and will be subject to the same regulation as public offers of shares etc. As a result, token issuance programs will need to structure their sale processes to be either fully compliant with, or exempt from, the regulations; at the very least, they must remove any suggestion that these tokens are capable of creating security interests in financial or dividend-bearing assets, unless that is the express intention. (In some cases, these tokens are sold as membership services, software and IP licenses, or as network access permits. Any “return” to the buyer comes from the network value effects, service discounts or user rewards, similar to frequent flyer schemes and customer loyalty programs.)

Again, this suggests a coming of age for digital assets, and a growing maturity in the way token sales can be used as an alternative to VC funding and other traditional sources of raising operating capital and project financing.

The Bitcoin fork was hugely anticipated, with a mix of fear and excitement – fear because of the unknown consequences, excitement at the prospect of Bitcoin holders getting “free money” in the form of “Bitcoin cash“, via a 1:1 issue. Without getting into the technical details, the fork was prompted by the need to increase Bitcoin’s blockchain processing speed and transaction capacity; and while nearly everyone connected to Bitcoin’s infrastructure agreed on the need to accelerate block performance, there was a schism as to how this should be achieved. Some exchanges said they would not recognise the new currency, and only some Bitcoin miners said they would engage with it (especially as the cost of mining the new asset was more expensive than Bitcoin core). In addition, most exchanges were advising their customers not to attempt performing any Bitcoin transactions for several days, before and after the fork, until the system settles down again.

In the aftermath of the fork, at least one more exchanges has said it will probably offer some support Bitcoin cash; while due to the nature of the fork, Bitcoin cash’s own block processing time was something like 6 hours – meaning transactions could not be confirmed, and holders of the new asset could not easily transfer or sell it, even if they wanted to. It feels like a combination of a liquidity squeeze, a trading halt, and a stock split resulting from a very complex corporate action.

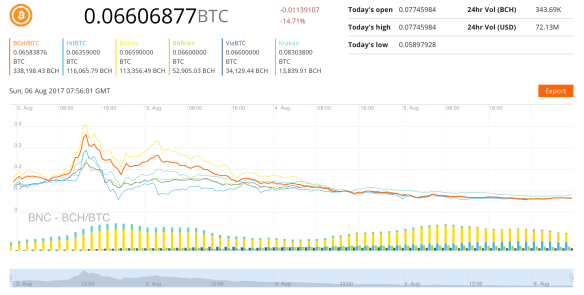
So far, the value of Bitcoin has held up, while the value of Bitcoin cash has steadily declined (despite an early spike), almost flat-lining to less than one-tenth of the value of Bitcoin:

Relative value of Bitcoin cash (BCH) to Bitcoin (BTC) – Market Data Chart sourced from Brave New Coin

I’m not a “Bitcoin absolutist“, as I think different currency designs and technical solutions will continue to emerge based on specific use cases. These products will continue to co-exist as markets come to understand and appreciate the different attributes and functionality of these digital assets.

As a consequence of recent events, some new token projects are refining the design of their issuance programs, more legal opinions are being commissioned, and raise targets are being adjusted in light of the current climate. But the number of new projects coming to market shows no sign of abating, and the better projects will have successful and sustainable sales. The total market cap of all digital assets is now well over $100bn (although the data reveals something of an 80:20 scenario – the top few assets account for the bulk of that value); and more institutional investors and asset managers are taking a greater interest in this new asset class.

NOTE: The comments above are made in a purely personal capacity, and do not purport to represent the views of Brave New Coin or any other organisations I work with. These comments are intended as opinion only and should not construed be as financial advice.

Next week: Bringing Back Banter