The Grey Ceiling

Last week I blogged about ageing rockers and the growing number of septua- and octo-genarian musicians still touring and recording. Perhaps they never got The Who‘s memo about hoping to die before they get too old? Anyway, it’s enough to make you think  Jethro Tull should update the lyrics to their 1970’s song….

Over in the world of sport, it seems ageism is still a thing. At the Australian Tennis Open in January this year, there was much media commentary (even surprise, disbelief and incredulity) that a 43-year old player reached the men’s doubles final, and had the temerity to win. In doing so, he become the oldest Grand Slam winner, and oldest to achieve a #1 ranking. Goodness knows what those same sports writers will make of a 41-year cricket player becoming the first fast bowler to claim 700 Test wickets.

Meanwhile, the US Presidential election looks like it will be fought out between an increasingly frail 81-year old incumbent, and an erratic 77-year old challenger, who has the audacity to say his adversary is not fit to stand on grounds of age and cognitive impairment. (To say that this contest will be far from elegant or dignified is an understatement!)

However, very few of us ever get to run for President – but most of us will experience something akin to the Grey Ceiling. We will reach a point in our working life when we are considered too old for promotion, or too old to hire, or too old to be retrained, or too old to be kept on.

In some roles and industries, there are compulsory retirement ages. And I get that.

What I can’t understand is the notion that just because someone is in their 50s or 60s, they are on the scrap heap of their career. The last time I was made redundant from a corporate role in a multinational organization, I had just turned 50. I can’t prove anything (because that would be age discrimination), but I had sense that it was “easier” for the company to let me go than a younger colleague: I had no dependencies, I hadn’t quite reached the full entitlement of long service leave, and I was not an expat so there were no relocation costs to consider.

At one job interview following that redundancy, the interviewer had the audacity to suggest that due to my age, experience and seniority, I would be less likely to “get my hands dirty” with day-to-day business operations and commercial decisions, and more likely to sit back and “direct traffic”. There was also a suggestion that I would be less willing/able to adapt to new technology, giving the overall impression he thought at my age, I was simply looking for an easy life.

Thanks to such attitudes which I also encountered elsewhere, I am glad I went to work as a freelance consultant and contractor with smaller businesses, start ups, owners and founders, and also in the cutting-edge technology of blockchain, crypto and digital assets – I have learned so much more in the past 10 years than I probably did in the previous 20 years of my career.

One thing I definitely don’t miss from corporate life is office politics!

And if neither ageing rock stars, nor 40-year old sports people at the peak of their careers, inspire you in your own journey (or as you hit the Grey Ceiling), perhaps some of the stories in The Guardian’s “Life After 60” series will inspire you.

Next week: Unstructured Hours


BYOB (Bring Your Own Brain)

My Twitter and LinkedIn feeds are full of posts about artificial intelligence, machine learning, large language models, robotics and automation – and how these technologies will impact our jobs and our employment prospects, often in very dystopian tones. It can be quite depressing to trawl through this material, to the point of being overwhelmed by the imminent prospect of human obsolescence.

No doubt, getting to grips with these tools will be important if we are to navigate the future of work, understand the relationship between labour, capital and technology, and maintain economic relevance in a world of changing employment models.

But we have been here before, many times (remember the Luddites?), and so far, the human condition means we learn to adapt in order to survive. These transitions will be painful, and there will be casualties along the way, but there is cause for optimism if we remember our post-industrial history.

First, among recent Twitter posts there was a timely reminder that automation does not need to equal despair in the face of displaced jobs.

Second, the technology at our disposal will inevitably make us more productive as well as enabling us to reduce mundane or repetitive tasks, even freeing up more time for other (more creative) pursuits. The challenge will be in learning how to use these tools, and in efficient and effective ways so that we don’t swap one type of routine for another.

Third, there is still a need to consider the human factor when it comes to the work environment, business structures and organisational behaviour – not least personal interaction, communication skills and stakeholder management. After all, you still need someone to switch on the machines, and tell them what to do!

Fourth, the evolution of “bring your own device” (and remote working) means that many of us have grown accustomed to having a degree of autonomy in the ways in which we organise our time and schedule our tasks – giving us the potential for more flexible working conditions. Plus, we have seen how many apps we use at home are interchangeable with the tools we use for work – and although the risk is that we are “always on”, equally, we can get smarter at using these same technologies to establish boundaries between our work/life environments.

Fifth, all the technology in the world is not going to absolve us of the need to think for ourselves. We still need to bring our own cognitive faculties and critical thinking to an increasingly automated, AI-intermediated and virtual world. If anything, we have to ramp up our cerebral powers so that we don’t become subservient to the tech, to make sure the tech works for us (and not the other way around).

Adopting a new approach means:

  • not taking the tech for granted
  • being prepared to challenge the tech assumptions (and not be complicit in its in-built biases)
  • question the motives and intentions of the tech developers, managers and owners (especially those of known or suspected bad actors)
  • validate all the newly-available data to gain new insights (not repeat past mistakes)
  • evaluate the evidence based on actual events and outcomes
  • and not fall prey to hyperbolic and cataclysmic conjectures

Finally, it is interesting to note the recent debates on regulating this new tech – curtailing malign forces, maintaining protections on personal privacy, increasing data security, and ensuring greater access for those currently excluded. This is all part of a conscious narrative (that human component!) to limit the extent to which AI will be allowed to run rampant, and to hold tech (in all its forms) more accountable for the consequences of its actions.

Next week: “The Digital Director”


“What Should We Build?”

Over the past week, the Leader of the Federal Opposition has been asking a series of questions on Twitter and elsewhere, about “what should Australia be building?”. As well as building the foundations of Labor’s Federal Election policy platform for boosting jobs in the manufacturing sector, it also provides lots of photo ops for pollies in hard hats and hi-viz clothing. (I do wonder why the potential Prime Minister hasn’t thought of this idea before, or why he appears to not know the answer – isn’t that his job? It also makes me wonder whether we need Parliament anymore, since our elected representatives prefer to conduct their “debates” via Social Media and Press Conferences…. it would save a lot of time and money!)

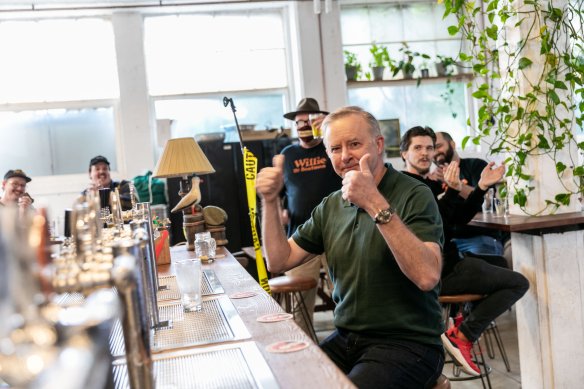
By this time next year, Albo could be PM (Photo sourced from Twitter)

There has been no shortage of suggestions from the Twitterati, which fall into the following main categories:

  • Renewable energy
  • Trains
  • Trams
  • Ferries
  • High-end engineering

But there has also been commentary around Labor’s ambivalence on the coal and gas sector (especially in the key state of Queensland), and the irony that we export cheap raw materials and import expensive finished goods. Then there is debate on the amount of local manufacturing content that already exists in Australia’s state-based trains and urban trams/light rail systems (skewed by the question of local vs foreign ownership). Plus, there’s the thorny issue of high-speed inter-city trains…

As I commented recently, the manufacturing sector accounts for fewer than 1m local jobs (less than 10% of the working population), and 6% of GDP. It has been declining steadily as a contributor to GDP since the 1960s, and more rapidly in recent years since we abandoned key subsidies to the car industry. I don’t think anyone is suggesting we return to the days of metal bashing and white goods. And while we’ve got to be selective about the type of manufacturing base we want to to develop, we also have to be realistic about the manufacturing capabilities we want to encourage and enhance.

The latter involves developing transferable skills, creating interoperable production lines, deploying modular designs and inter-changeable components, and recycling/repurposing. All of which should mean we don’t need to make every part of every item domestically, but we know how to assemble, service, maintain, repair and replace goods locally, and we can focus on adding value that can be fed back into the supply chain, which in turn can be exported (via know-how and services). Australia has some decent research and development capabilities, but we are not always very good at raising domestic investment, or commerciliasing our IP (so this value ends up being transferred overseas, with little to no return accruing locally).

I’m not a huge fan of simplistic “buy local goods/support local jobs” campaigns, or local content quotas. The former can degenerate into trade protectionism and economic nationalism; while the latter tend to favour inefficient incumbents within cozy duopolies (see the broadcasting and media sector). The current debate has also raised questions about procurement policies, and I for one would welcome a total revamp of government IT purchasing and deployment at Federal, State and LGA levels.

There’s also the consumer angle: Australians are notoriously “cost conscious”, so will they be prepared to pay more for locally-made goods, even if they are better designed, well-made and energy efficient, compared to cheaper, less-sustainable imports? (This is also linked to the question of wage growth and restrictive trade practices.)

The recent pandemic has highlighted some challenges for the structure of the local economy:

  • Disruption to distribution networks and supply chain logistics
  • Food security
  • Energy self-sufficiency
  • Inability to service equipment locally or source spare parts
  • Different standards across the States
  • Medicine and vaccine manufacture, sourcing and distribution

For an up-to-date perspective on where Australian manufacturing policy needs to be heading, I recommend taking a look at the Productivity Commission’s latest submission to a current Senate enquiry. (Am I alone in thinking that the PC, along with the ACCC, is doing more to develop and advance economic policy than our elected representatives?)

The PC’s submission addresses a number of key points:

  • R&D incentives are hampered by complex tax treatment
  • Policies (and subsidies) favouring one industry create uncertainty for others
  • Need for IP reform (especially “fair use” of copyright)
  • The National Interest test needs clarifying
  • More effort on up-skilling through more relevant education and training
  • The role of manufacturing capabilities in supporting supply chain infrastructure

Finally, while I agree that there needs to be some focus on renewable energy and public transport, we should not ignore food and agriculture, bio-tech, IT, automation, robotics, materials science and other high-end capabilities in specialist design, engineering and recycling (including reclaiming precious minerals from obsolete equipment).

(And did I mention the “Innovation Agenda” and the revolving door at the Federal Ministry?)

Next week: Dead Pop Stars

Where is wage growth going to come from?

How good is the Aussie economy? On the back of the stable outlook on our AAA sovereign credit rating, last week’s employment data showed a better-than-expected post-COVID recovery in terms of the headline unemployment rate and overall workforce participation. This has led to speculation of a potential uplift in wages, due to labour shortages amplified by the current halt on immigration (thanks to closed borders).

But where will this expected wage growth actually come from?

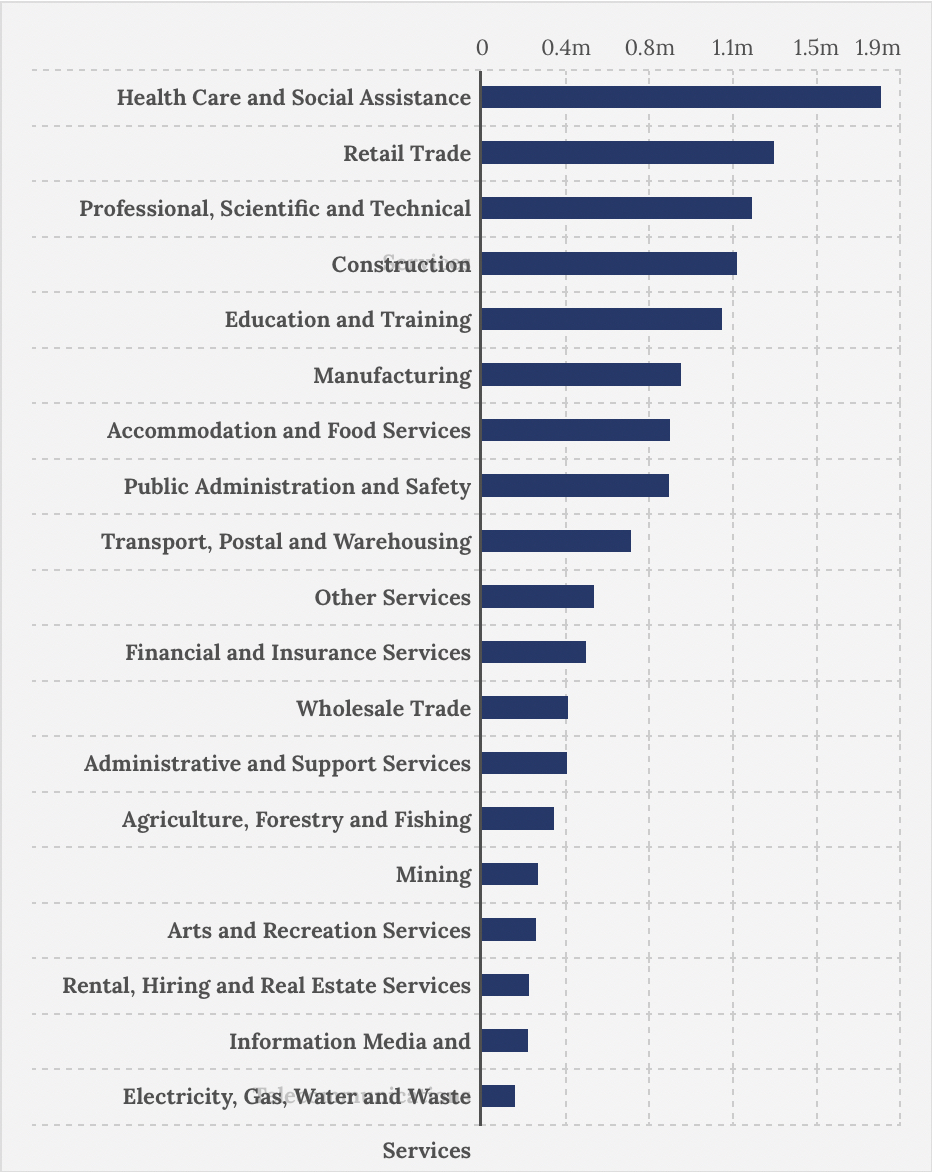
According to ABS data for February 2021, the top 5 industries by number of people employed are: Health Care; Retail Trade; Professional, Scientific and Technical; Construction; and Education. (See above chart.)

Now, contrast this with three other relevant data points: 1) the number of Australian companies by size; 2) the annual change in employment growth/reduction by industry; and 3) the national GDP contribution by industry.

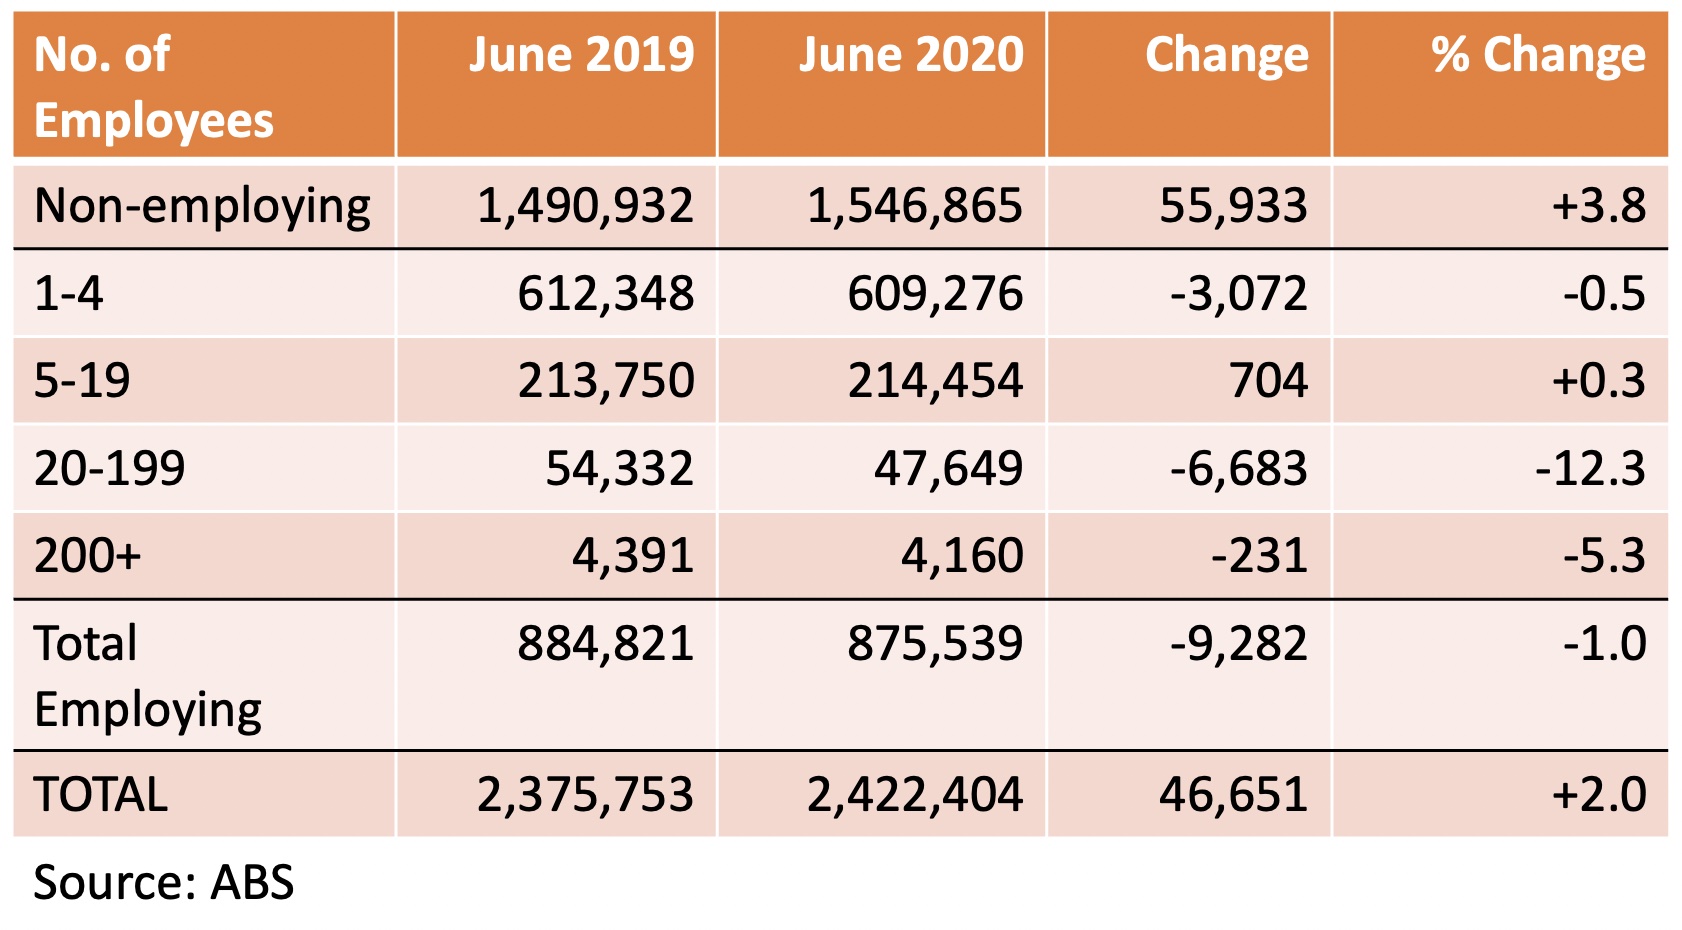
First, there are nearly 2.5m registered business entities, according to ABS data. Over 1.5m of these are designated as “Non-employing” – including sole traders, self-employed, independent contractors or freelances. Over 850 thousand establishments employ fewer than 200 people. Fewer than 5,000 businesses employ more than 200 people. Although there was an overall growth of 2% in the number of registered businesses, the largest increase was in the “sole trader” category, while the largest decreases were among medium-sized companies, and large enterprises. (See table below – the next ABS data is due in August.)

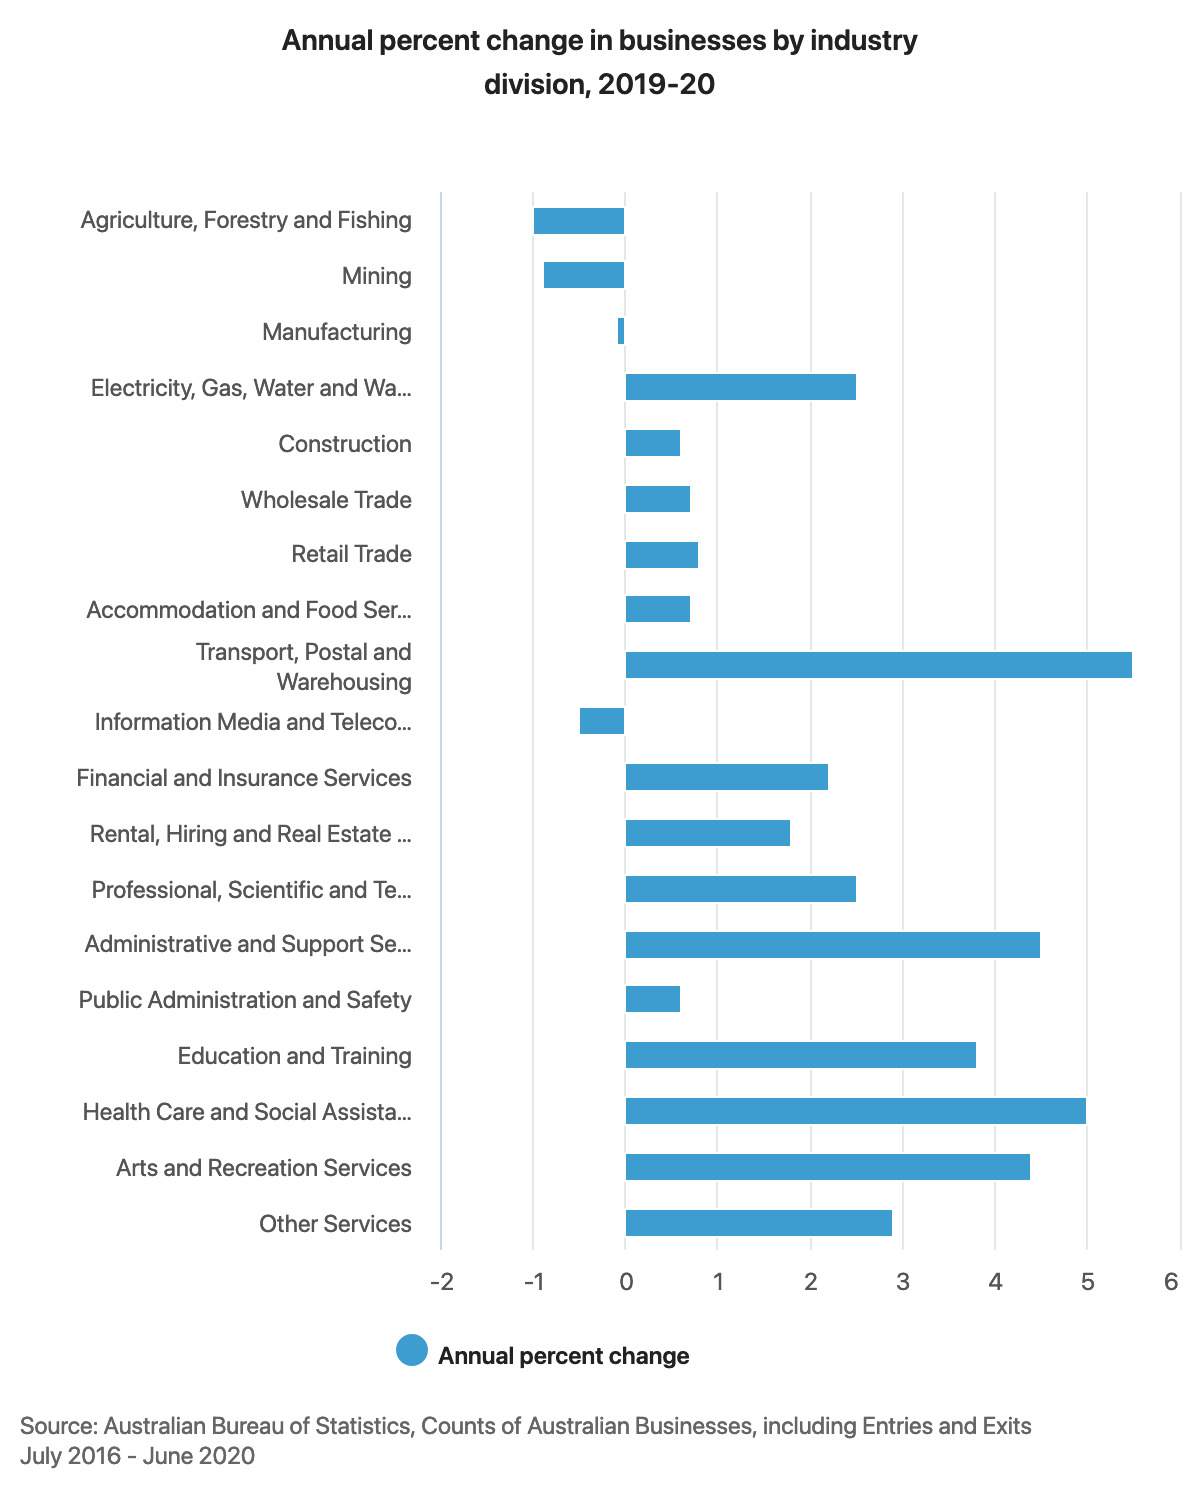
Second, the largest employment growth by industry sector in 2019-20 came from logistics and healthcare – no doubt in large part to the impact of COVID. Primary industries and mining both registered decreases.

Third, the main contributors to output (GDP) are Health and Education (13%), Mining (11%), Finance (9%), Construction (8%) and Manufacturing (6%) – based on a recent RBA Snapshot. But the data is always subject to further examination and clarification – for example, while construction employs over 1.1m people, many of these are engaged as independent tradies or through sub-contractors, and in spite of the huge number of major infrastructure projects (just look at Victoria’s Big Build and all the cranes in Melborne CBD), there was only negligible growth in overall employment within the sector. And while mining is a major contributor to GDP, it does not employ huge numbers of people (it’s actually on a par with the arts…), yet the fewer than 9,000 people who are employed as mining engineers are in the top 10 occupations by salary (according to ATO data analysed by the ABC.)

Some other factors to consider as we ask, “Where will wage growth come from?”:

  • While most people are employed by SME’s, these companies are probably under the greatest strain when it comes to overheads and inputs, as they have relatively high fixed costs, and can ill-afford higher wages in the current trading conditions.
  • On July 1, the Superannuation Guarantee is due to increase from 9.5% to 10% – some commentators suggest employers (especially SMEs) may have to reduce or offset wages to pay for the scheduled increase.
  • We have an apparent choice between an asset-led recovery (inflated house prices – but risks leaving people “asset rich and cash poor” when interest rates go up ); a consumption-led recovery (reliant on higher wages so people feel comfortable to spend money); or an investment-led recovery (businesses need to invest in new equipment and projects to boost productivity, and not just bring forward planned expenditure thanks to tax incentives).
  • The sectors where we need more people (health care, aged care, child care and education) are still among the lowest paid on a per capita basis.
  • What is happening to boost manufacturing, or aren’t we interested in making things anymore?
  • Our IT and technical skills shortages have been exacerbated by the absence of overseas students and graduates – there is anecdotal evidence of wage and hiring pressures in this sector, one which is probably more important to our future economy and sustainability than mining coal or building more roads.
  • One leading economist reckons that household incomes have increased by 30% over the past 10 years. If wages have been stagnant, where has this growth come from? Is it because of tax cuts, low interest rates, quantitative easing, real estate prices (or their crypto holdings)? And do we actually feel any wealthier as a result?

Finally, will inflation and/or interest rates undermine any potential increase in wages?

Next week: Is Federation still working?