The changing economic relationship of #work

Whether or not we are comfortable with the notion, the work we do can come to define us. In some societies, family names are derived from our forebears’ occupations or professions (Butcher, Baker, Smith, Cartwright, etc.).  The rapid shift to the knowledge economy is challenging our traditional economic relationship with work, and what it means to be an employer or employee. For example, the idea of a “job for life” within the same industry, let alone the same company, is no longer the norm.
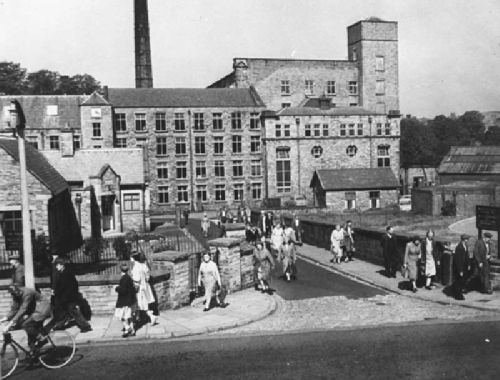
Workers leave Waterhouse Mill, Bollington, Cheshire, UK (1959)

Workers leave Waterhouse Mill, Bollington, Cheshire, UK (1959)

“Welcome to the working week”

This past week I have been listening to the latest thinking on the nature of “work”, from the perspective of technology and its impact on task-based activity (courtesy of Donald Farmer from Qlik), and from the perspective of organizational culture and its importance in motivating knowledge workers (courtesy of Didier Elzinga of Culture Amp). If you are not familiar with either of these thought leaders, than I thoroughly recommend them to anyone interested in organisational behaviour, career development, business transformation and lifelong learning.

Technology and changing demographics require each of us to reframe our ideas about work as a homogenous lifelong activity, because the economic bargain between employer and employee is no longer as simple as a 40 hour working week and a regular paycheck.

Reframing “employment” #1:

By 2020, average job tenure will be 3 years, and around one-third of the workforce will be employed on a casual basis (part-time, temporary, contractor, freelance etc.). The proliferation of services such as Freelancer, O-desk/Elance, Sidekicker, 99designs, Envato and Fiverr are evidence of this shift from employee to supplier.

“The Dignity of Labour, Pts. 1-4”

Around 200 years ago, at the height of the Industrial Revolution in England, the typical worker was employed in a factory or mill, lived in housing owned by the employer, and was paid some or all of his wages in the form of vouchers that could only be spent in shops also owned by the employer. A hundred years later, my grandparent’s generation were still exposed to the practices of indentured labour (“master and servant”) or the idea of “going into service” (as domestic workers). My father’s generation is certainly the last in my family to have had a 30-year salaried career within the same organisation.

So, in just a few generations we have transitioned from the idea that employment provides for all our needs, to the increasingly common perception that every worker is in fact a micro-business, supplying their labour to multiple employers or clients via fee-based services. (The potential irony here is that in a world of freelancers and contractors, the time-based or task-linked approach to employment pricing starts to resemble Marx’s idea of the labour theory of value…..).

“Cottage Industry”

It’s also interesting to note that before workers were employed in factories, and as agrarian labourers transitioned from toiling in the fields to working in manufacturing production, they were hired on piece-rates, working from home in the form of (literally) cottage industries. Of course, this was not exactly self-employment, as their tools (looms and lathes) were probably provided by their “client” who also set the prices (for raw materials and finished goods), had exclusive rights over the finished goods, and determined the number of units required. But, within the constraints of meeting target numbers and societal norms such as Sunday observance and customary holidays, these labourers were “free” to work for as many hours as they wanted, and at times that suited them. So, like many contemporary issues we still seem to be struggling with, flexible working arrangements are nothing new….

“Work is a four-letter-word”

Aside from connecting with your purpose, understanding your personal value proposition and knowing what you are “worth” in the market, one of the biggest challenges I see for employees/workers is the paradox between shorter careers (witness the increasing unemployment rates among older workers) and longer working lives.

Thanks to medical advances, we are living longer, but there is a mismatch between workforce participation rates and increased welfare and social security costs, leading to continuous policy tinkering on pensions, tax and superannuation.

As individuals, we need to build up sufficient financial assets to sustain us both post-retirement, and during erratic periods of personal income. As “free agents”, we have to learn to live with:

  • increasing job insecurity (companies continuously de-layering and restructuring)
  • significantly different career paths (compared to personal aspiration/expectation)
  • rapidly changing working environments (hot-desking, co-working spaces)
  • greater self-reliance (“bring your own device”) and
  • heightened resilience (“shape up or ship out”)

“Opportunity”

The good news is that the model of portfolio, portmanteau and protean careers means that new jobs and new forms of working are emerging all the time – and with personal resilience etc., come flexibility, adaptability, knowledge sharing, skills transfer and new opportunities for personal development, along with self-defined roles, self-directed learning, self-managed performance and self-determined accountability.

We are no longer defined just by what we do, but how/where/why/when we do it.

Reframing “employment” #2:

A friend recently asked me for some advice on how to transition from “employment” to “self-employment”. She has regular part-time work with one organisation (which she views as employment), but wants to find more of her “own work” with other clients. She does not want to give up the part-time gig just yet, but feels that it is preventing her from growing her own business. So I suggested that she should see herself as being self-employed already, and that the part-time work is her first client, allowing her to build a portfolio of new business.  

“Earn enough for us”

What does this brave new world of work mean for employers – in particular, what is the new economic bargain organisations need to have with their workers?

If companies are no longer willing/able to offer long-term, permanent employment opportunities, how do they manage their labour requirements, attract and retain the best talent (when they need it), and engage highly motivated and skilled people?

First and foremost, the idea of workplace flexibility has to be truly reciprocal – but obviously aligned and clearly articulated – to be of any real benefit to both parties.

Second, if employers are increasingly reliant on freelance resources, this does not obviate their obligations to invest in their workforce – whether that includes benefits, training or rewards and recognition – the same as they would have in their employees.

Third, companies will need to do an even better job of attracting and retaining the skills and knowledge they require – and be willing to offer different kinds of incentives (e.g., opportunities to work on engaging projects and to collaborate with interesting people) beyond basic pay and conditions.

Fourth, employers may have to adjust to the idea of “syndicating” their talent resources (“it’s the shared economy, stupid”) not just within their own workplaces, but across their client organisations, suppliers, service providers and other collaborators – sometimes, even their competitors. Employers can no longer expect to have a total monopoly on their workforce talents, unless they make it really interesting, financially or otherwise…

Fifth, if companies continue to espouse the message that “our people are our best asset” then they need to update their asset management model to demonstrate they mean what they say. For example, more needs to be done in helping employees to retrain and up-skill (for jobs and roles that haven’t yet been thought of), even if that may mean employees are more likely to move on. The amount of goodwill that this will create in the wider community cannot be underestimated.

Reframing “employment” #3:

Employers and HR managers are re-assessing how they evaluate employee contribution. It’s not simply a matter of how “hard” you work (e.g., the hours you put in, or the sales you make). Companies want to know what else you can do for them, how you collaborate, do you know how to ask for help, and are you willing to bring what you know to the role?  

Finally, rather like their employees, employers are increasingly expected to connect with their purpose and to align their values with their objectives. New entrants to the workplace are better informed about the organisations they work for and want to work for, because free agents know they have a choice.

Next week: How to work with Boards
Connecting Investors and Founders

In recent weeks I have been listening to business founders and investors talk about what each party is looking for in the other when it comes to striking a potential deal. We know that due diligence, planning and preparation as well as financial analysis are all critical to success – but investors are essentially buyers, and as with any product or service, people buy from people. More often than not, relationships based on a common connection, mutual respect, purposeful rapport and personal interaction will form the basis of most investment decisions.

Here are some examples of what you might expect to encounter when thinking about selling your own business, or bringing in external investors.

handshake-220233_1280

What are investors looking for?

At a networking event hosted by Startup Victoria, established investors talked about their criteria for investment.

First and foremost, investors need to know the business you are in (the basic principle being “if you don’t understand it, don’t invest in it”). In the case of an early-stage business, investors also need to know how/where they can add value, since they expect to be more involved with the strategy and execution.

Second, as explained at a workshop hosted by AICD/KPMG, there are only a few types of transactions:

  • Strategic – such as a trade buyer or targeted M&A transaction
  • Financial – such as a Private Equity fund or Family Office
  • Succession – a management buy-out or generational transfer
  • Public – an Initial Public Offer, such as an ASX listing

Each will have their preferences and processes, and as a business owner or founder, you need to understand what each option means for you. Your interests need to be fully aligned, otherwise all the planning and due diligence in the world won’t prepare you for potential disappointment, unmet expectations or even a failed transaction. For example, as a founder wishing to sell your business, are you prepared to see the new buyer shut down one of your cherished products?

Third, financial and strategic investors will have very specific objectives and timelines. As one early-stage investor said: “I’m not a lifestyle investor”, meaning, “I don’t invest in a business to fund your lifestyle” (I invest to fund my own lifestyle…). So, the goal is to invest, drive growth and exit within 3-5 years having generated a target multiple of return on investment. Another investor took a contrarian view, commenting that he had never yet sold out of any business he had invested in – because he takes a longer perspective, and he likes the people he invests in.

Finally, and following on from the last point, investors (especially in start-ups and founder-operated businesses) are often buying the people and the team, not just the business. This prompted the comment about “can you have a beer” with the business owners or founders? The “getting to know you” process is very important for establishing the relationship, exploring what each party is looking for, and framing the nature and terms of the transaction.

What are founders and owners looking for?

Apart from money, what else might you be looking for when contemplating a business sale or bringing in external investors?

Depending on what stage your business is, you will likely need capital for specific purposes, or you may be looking for a particular type of investor. So, know what type of funding you require, and what you might be expecting from the investor.

If it’s contacts and introductions you want, then as shows like Dragons’ Den and Shark Tank demonstrate, investors will extract a high price in return for opening up their precious address books.

Just as investors check out the people as well as the business, owners who are seeking external funding should really do their homework on prospective investors – especially when it comes to unsolicited or unexpected offers to buy your business.

One speaker (who has been on both sides of the transaction) noted that he was wary of a particular investor, because he knew that the relationship would be difficult – a feeling that was borne out by problems at board meetings, and challenges getting shareholder alignment and agreement on critical strategic decisions.

Even if as a founder you are seeking to exit your business via a trade sale or equity transaction, in many cases the new owners or investors will expect you to stay on in the business, to maintain continuity. As is frequently the case, the owner’s sale proceeds will be subject to an earn out to ensure the business meets its projected forecasts.

I have known some entrepreneurs who have left a corporate role to start a new business, with the specific aim of being acquired by their former employer – and I know of at least one such founder who has managed to do this more than once, but a condition of purchase is usually golden handcuffs linked to a performance target.

Other Considerations

There is a commonly held view that if you don’t need to bring in external investors, then you should hold out as long as possible. It’s also said that debt is cheaper than equity, and with current interest rates at a record low, borrowing from a bank or other lender is quite possibly a better option.

However, as I have written previously, there are several obstacles to getting startup funding, especially from banks. In particular, banks prefer secured lending, so if you don’t have sufficient assets (or if you are reluctant to put the family home at risk), and if you don’t have consistent cashflow (for factoring or invoice discounting purposes), your borrowing options will be limited.

An alternative to either bringing in external investors or taking out a loan might be to enter into a joint venture or similar partnership that gives you access to cash and other facilities, while retaining control of your business. For example, a JV to develop a new product or enter a new market can de-risk the opportunity, while enabling you to leverage skills or other expertise that you may not have.

If you are intending to sell your business, even one that is a mature and going concern, most advisers will tell you that the planning and preparation will take 2-3 years, especially as buyers will likely want to see a minimum of 3 years’ trading information and financial records. Don’t underestimate the time it will take to pull together the accounts, document key aspects of the business such as IT systems and processes, catalogue the IP, consolidate CRM and client account information, get a valuation and ensure key personnel are in place as part of the transition team.

Finally, don’t forget to obtain professional tax and accounting advice – I’ve heard business advisers lament the fact that many retiring business owners just about realise enough money to pay off their mortgage, once the sale transaction costs, business debts and tax bills have been settled.

Next week: The changing economic relationship of “work”

Will streaming kill the music industry?

The resurgence in vinyl sales is certainly not enough to save the music business. But will streaming finally cook the goose that once laid Gold Discs?

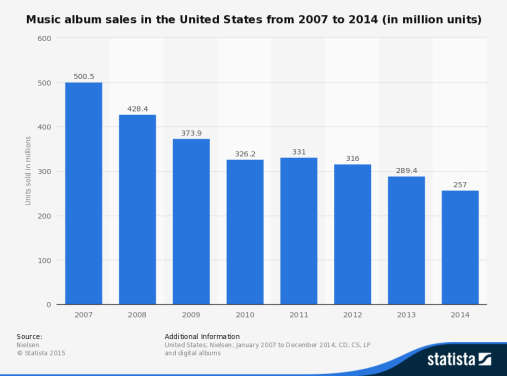
statistic_id273308_music-album-sales-in-the-us-2007-2014

US album sales (in all formats) are in decline. (Source:  Statista)

What can we learn from the music industry based on the apparent rebound of vinyl sales in recent years? Is streaming doing enough to halt the decline in total music revenue? Will CD’s soon disappear altogether? What future for LPs in a world of “Album Equivalent Sales”, “Track Equivalent Albums” and “Streaming Equivalent Albums”?

Are there parallels here with other content, publishing or entertainment sectors?

Back to Black

Last month the 8th annual Record Store Day was launched with a fanfare of upbeat data for vinyl sales. It was a good news story in an otherwise depressing saga of declining album sales, stagnating revenues, and mixed messages about the impact of digital downloads and streaming services on the music industry.

Coming off a very low base (like, near-extinction levels), the extraordinary sales growth of vinyl (especially in Australia) can be attributed to a combination of factors, although it is difficult to see how any single trend is responsible for this growth:

  • The growing popularity of Record Store Day itself (although it’s not without its problems – see below)
  • Baby boomers buying their record collections all over again
  • Hipster interest in analogue technology
  • Record labels mining their back catalogues
  • Niche market interest among audiophiles, collectors and the cool kids
  • New approaches to packaging vinyl with downloads and other bonus content
  • DJ culture
  • Secondary markets via E-bay and Discogs
  • Retailing switching from megastores to specialist shops

Infographic: Vinyl Comes Back From Near-Extinction (Source: Statista)

Where Is The Money Coming From?

Latest industry data suggests that digital sales (downloads and streaming) are now on a par with physical sales (CD, vinyl and the rest). Overall revenue has stabilised, having fallen from a peak in 1999. And streaming services are enjoying huge growth.

But the true picture is harder to establish:

First, while the IFPI provides global aggregated data, each local industry body (RIAA, BPI, ARIA etc.) likes to tell a different story from its national perspective. So it’s difficult to compare like with like. (For example, while Taylor Swift is supposed to be a worldwide phenomenon, she does not figure at all in the BPI data for 2014…..) One brave soul has tried to compile data for the past 20 years.

Second, because of the changes in distribution and consumption, music sales have to be counted in different ways:

  • Wholesale revenue vs retail sales
  • Physical sales vs digital sales
  • Per unit download sales vs streaming equivalents
  • Product revenues (e.g., album sales) vs licensing revenues (e.g., soundtracks)
  • Subscription fees (e.g., Spotify) vs per download revenue (e.g., iTunes)
  • Advertising income from video streaming vs royalties from broadcasting and soundtracks

Third, when more and more music is accessed via video platforms like YouTube, Vimeo, and Vevo, streaming platforms like Spotify, Pandora and Omny, or apps such as Bandcamp, Soundcloud, Mixcloud and Shazam, “sales” data starts to become less and less relevant. (And some people are still hanging on to the ailing MySpace platform….).

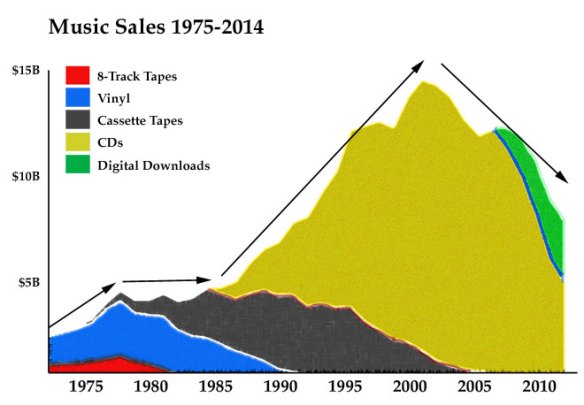
The bottom line is that despite the growth in streaming services, digital sales (in whatever format or media) are not yet enough to compensate for the continued decline in album sales in particular, and music overall:

The peak era of CD sales is over. (Source: Talking New Media)

Record Store Day Woes

The success of Record Store Day has divided opinion as to whether it is actually a “good thing” for the industry. It started as a campaign by independent record labels, distributors and retailers to revive the habit of buying records in-store. Labels produce limited edition and often highly collectible items for the occasion, and there are rules as to how, when and where these releases can be made available to the public.

At first, it really was driven by the independent labels, many of whom brought out interesting product that otherwise wasn’t available, such as label samplers, unreleased material and one-off artist collaborations.

Now, the major labels have jumped on board, meaning the market is flooded with unnecessary re-releases (do we really need Bruce Springsteen‘s ’70s and ’80s albums reissued on vinyl?) drawn from their extensive back catalogues (no need to pay for recording costs or new artwork!).

This means that smaller labels who release new vinyl records on a regular basis (not just once a year) get bumped from the production line, as the major labels exert their purchasing power over the pressing plants.

In addition, some Record Store Day releases are so badly distributed that stores are unlikely to take delivery of the items in time for the event. Or bad decisions lead to over-supply of certain items, which end up in the bargain bins (major labels again especially guilty of this offence).

Some store owners appear reluctant to participate because they feel embarrassed about the prices they may have to charge for many of the limited releases, which get bought by speculative customers, rather than collectors, fans and enthusiasts – a fact borne out by the immediate listings and inflated prices on E-Bay and Discogs….

As one store owner I talked to commented: “Every day should be record store day…”

What Else Does The Data Reveal?

For all the new young pop stars that the industry keeps churning out, there’s nothing like longevity and back catalogue to prop up the sales numbers. For example, Barbara Streisand was in the Top 10 for US album sales (and with new material!), and the likes of Pink Floyd, Led Zeppelin, Miles Davis, Bob Marley and Oasis feature in the top-selling vinyl records. Will Record Store Day 2025 herald the vinyl release of Justin Bieber’s pre-pubescent “demos”?

The decline of album sales has been particularly steep in the genres of Hip-Hop and R&B, while rock and pop continue to dominate the market. Some industry commentators have suggested that music sales are merely “in transition” as consumers switch from buying CD’s and downloading music to subscribing to streaming services. Meanwhile, in the US, country music’s #4 position by overall consumption reflects substantial album sales, as streaming is still a small component for the genre.

And those vinyl sales numbers? They’re simply a blip on the chart and largely driven by avid fans willing to shell out for deluxe editions….

The future is streaming?

Apple and others certainly believe (or hope) that streaming will save the music industry. Having demolished the market for CDs, iTunes is in a battle for its own survival among competing streaming services, where Apple itself is about to lead the charge having acquired the Beats platform.

But others are not so sure, predicting that streaming is already in decline, along with download sales:

First, the streaming platforms are yet to make a profit. Part of this is due to the cost of content that has to be licensed from the record labels and artists. Part is also due to the cost of acquiring customers, even if this can be done via social media, because the decline in music buying has been so abrupt, so the industry may be permanently damaged that streaming cannot bring back paying customers.

Second, even though streaming may overtake downloads by next year, there’s still nothing certain that teen pop fans (the target audience) will pay $7.99 – $9.99 per month to listen to music via so-called “freemium” services. Evidence suggests that consumers are happy with the free services, even if they have to put up with ads.

Third, while I agree that the freemium model is a fixture in the digital economy, the problem with Spotify et al is that they are not growing the market for music, but simply cannibalising it by displacing existing platforms (commercial radio, digital downloads, physical sales), while being tied to third-party distribution channels (the internet) and devices (smart phones, tablets and computers).

Anyway, subscription-based music streaming is nothing new, and was first launched over 100 years ago (and thanks to Mark Brend’s “The Sound of Tomorrow”, I learned that Mark Twain was the first subscriber).

If the “old” record companies are charging streaming services too much to license their content, then the streaming services should just find other sources – there’s plenty out there – but then, just like the major record labels, they are not really interested in music, only in shifting product and promoting “artists” (even if they are still figuring out how to make digital pay). The record labels don’t help themselves with their reliance on back catalogue, and their archaic territorial licensing practices either – forcing customers to circumvent geo-blocking barriers (legally or otherwise…).

Unfortunately, file sharing, illegal downloads and “free” streaming have meant customers don’t feel compelled to pay for digital music content. Personally, I prefer to curate my own listening, and not let someone else dictate what I hear, even if the service “knows” my preferences…

And the moral of the story is…?

More distribution platforms, more formats and more content may not be enough to save ailing industries, whether it’s music or television, newspapers or movies. These businesses will have to learn to live with lower margins and/or smaller market shares. The quality of a home-made movie uploaded onto YouTube may not be anywhere near that of a Hollywood blockbuster, but if cat videos are what grab punters’ attention (and by default, pull in the advertisers), the studios may have to find alternative strategies. And if music fans prefer to use free streaming services, the industry has to do a better job of producing content that consumers may be willing to pay for.

Ironically, in publishing, one sector that has been written off ever since the arrival of CD-ROM’s and the internet, teen consumers are still happily buying and reading print editions, alongside e-books. More so than other content industries, publishing has rapidly adapted to the new user-defined model: aspiring authors find it easier to self-publish (e.g., via Tablo and dedicated crowdfunding platforms such as Pubslush and Unbound); they can easily connect with an audience (especially in the realm of fan fiction); and a platform like Wattpad allows writers to test material before they commit to formal publication, and lets readers vote for what they’d like to read more of.

Next week: Making connections between founders and investors


Taxing the Intangibles – coming soon to a screen near you!

No sooner had Netflix launched in Australia than Treasurer Joe Hockey announced the imposition of GST on “intangibles” purchased from overseas vendors. The Treasurer has also indicated that the GST-free threshold for on-line imports will be lowered from the current $1,000. Dubbed the “Netflix tax”, Australian consumers should now expect to pay more for their digital content such as video, music, software and e-books, even though on most evidence, we are already charged more for comparable products than in other markets.

Geo-blocking is already an obstacle for Australian consumers…

Backdrop

We all know why the Treasurer has proposed this scheme: the Government has to make up for declining tax receipts, and appease the States who are squabbling over the allocation of GST revenue between them. Plus the current Senate inquiry into corporate tax avoidance by companies like Apple, Google and Microsoft (who divert locally sourced income to offshore entities to reduce their income tax liability in Australia) is driving the public and political agenda on global tax minimization schemes (which are nothing new, of course).*

But it’s not as simple as slapping an extra 10% on the price of a movie download, even though GST is a relatively easy and cost-effective way of generating tax revenue. For one thing, there is little consistency in how vendors currently sell their digital products in Australia. Secondly, geo-blocking is already an obstacle for Australian consumers, leading to the sort of content piracy infringement that will now make local ISP’s and their subscribers more vulnerable to legal action, following the recent “Dallas Buyers Club” court ruling. Thirdly, local retailers who have long campaigned to have the GST-free threshold removed or lowered fail to acknowledge why customers prefer to shop from overseas vendors.

Goods & Services Tax

GST (similar to VAT in Europe) is a simple consumption tax. It applies to the sale or supply of most items (except things like fresh food and health services) at a flat rate of 10%.

Even better, the Government and the tax authorities rely on businesses to collect, report and remit GST receipts, making it relatively cheap to administer (when compared to other taxes) via the Business Activity Statement process managed by the Australian Taxation Office.

The GST is a key topic of the current review of the tax system – likely to result in a higher rate (or different rates), and/or broader application to items not currently included.

Vendor Inconsistency

In principle, I don’t have a problem in paying GST on digital items I buy from overseas vendors – but there is so much inconsistency that there is a risk of consumers having to pay two lots of sales tax.

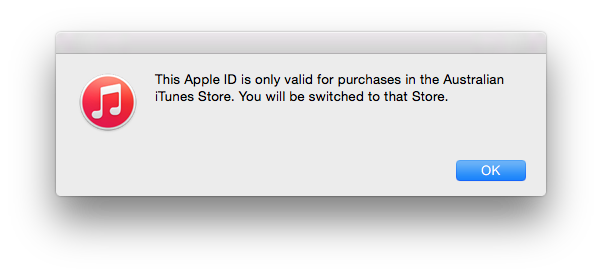
For example, every iTunes receipt issued by Apple Pty Ltd (an Australian entity) states that the sale amount already includes GST – in which case, Apple should be remitting that component to the ATO, and no need for a price increase.

However, Adobe chooses to invoice me from Ireland, and as such no GST (or VAT) is applied, but I am charged forex fees, even though the invoice amount is expressed in Australian dollars, because my bank treats this as a foreign transaction.

Meanwhile, although some UK vendors I buy from direct do not apply GST/VAT on my orders (Amazon UK included), others do – meaning I risk having to pay both the GST and VAT. As a further sign of vendor inconsistency, Amazon’s US store does not appear to deduct US sales tax for foreign customers; neither the UK or US Amazon stores sell music downloads to Australian customers; and Amazon’s Australian store only sells e-books and apps.

Geo-blocking

The decision in the “Dallas Buyers Club” IP infringement case brought by Voltage Films, has again drawn attention to Australia’s poor reputation for copyright piracy as evidenced by the number and frequency of illegal downloads.

Some journalists have commented that distributors often delay the local release of imported content (for various reasons) although this was not seen as a justification for piracy (and quite rightly so).

While foreign films are frequently released later in Australia, it’s interesting that TV (even free to air channels) has woken up to this, and now broadcasters rush to fast-track imported shows to keep audiences happy.

It’s also interesting to note that the Productivity Commission, as part of its competition policy review of IP laws, has suggested that if local rights holders and distributors choose not to exercise their commercial rights, under a “use it or lose it” model, third-party distributors would be able to step in. This also has the potential to undermine the archaic industry practice of geo-blocking, whereby sales of music, film and TV content (physical and digital) are restricted by territory.

Local retailers and distributors need to lift their game

Does the absence of GST really encourage consumers to buy from offshore retailers? I would beg to differ.

Local rights holders often do not bother to make content and products available in Australia. And local retailers won’t usually stock products if they are not readily available from wholesalers or distributors.

I recently had to contact an overseas artist, the UK record label and its Australian distributor several times to make their music available online in Australia. The local distributor had not bothered to release the content, even though they had the rights, but geo-blocking prevented me from accessing it legally from overseas suppliers.

It’s the combination of inadequate local distribution, non-availability, higher prices and lacklustre service that encourages Australian consumers to buy from overseas, even if that means circumventing geo-blocking. In many cases, I doubt the addition of GST will be a serious deterrent to online overseas shopping.

In my own case, I once found that the local branches of a global retail brand chose not to stock the item I wanted, and their US parent geo-blocked me from ordering on-line. So I resorted to buying in the “grey” or parallel imports market, from an offshore vendor willing to ship direct to Australia. It was still cheaper, even after shipping costs, and even if GST had been added (I probably paid US sales tax on the transaction anyway), than if I had bought from a local retailer (assuming they bothered to stock the item).

Hopefully, this debate on GST and the Productivity Commission’s review of competition policy will finally give local retailers an incentive to do a better job of serving their customers.

* The debate on corporate tax minimization might want to look at where “value” is created, and where the revenue is booked, that gives rise to a tax on the resulting profits. For me, the retail value of intangibles such as digital products is created when someone pays to download them, at the point of sale – i.e., in the consumer’s geographic location.  Although the vendor may argue that the IP is owned by an offshore entity to whom they must pay royalties, the individual download itself does not have any standalone value, until it is accessed by the consumer. Even a high rate of royalty repatriation could not be more than the retail price, so logic might suggest that local profits should be taxed accordingly.

Next week: What can we learn from the music industry?