Publishers’ Choice: Be a Victim, or Join the Vanguard?

I recently posted a blog about saving the Australian publishing industry, prompted by some research I was doing on government-sponsored initiatives, notably EPICS and BISG. This generated a couple of (indirect) responses, one from the Department of Industry itself, the other from a long-time colleague in the industry. More on these later.
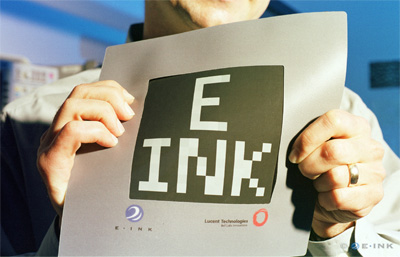
The future of publishing - circa 2000....

The future of publishing – circa 2000….

But first, some more industrial archeology, by way of demonstrating that book publishers are not shy about new technology – remember the first electronic ink? When I was working at the Thomson Corporation in the late 1990s, we were given access to a prototype version of what we would now recognise as an e-reader. It was about the size and thickness of a mouse pad but less flexible, and could only hold a small amount of data in its memory (content was uploaded via an ethernet cable). It was described as the future of book publishing, and was predicated on the idea of portability (it could be rolled up like a newspaper if the screen was thin and pliable enough), and updating it with new content whenever it was (physically) connected to a computer or the internet.

However, whatever their apparent appetite for new technology, publishers struggle to adapt their business models accordingly, or they are fixated on “old” ways of monetizing content, and locked into traditional supply chains, archaic market territories (geo-blocking), restrictive copyright practices and arcane licensing agreements; and unlike other content providers (notably music, TV and newspapers which have shifted their thinking, albeit reluctantly) the transition to digital is still tied to specific platforms and devices, unit-based pricing and margins, and territorial restrictions.

Anyway, back to the future. In response to my enquiry about the outcome of the BISG initiative, and the creation of the Book Industry Collaborative Council (BICC), the Department of Industry offered the following:

“A key outcome of the BICC process was to have been the establishment of a Book Industry Council of Australia, an industry-led body based on the residual BICC membership that would come to be a single point of policy communication with government, though following its own reform agenda in the identified areas and unsupported by any taxpayer funding. Terms of Reference and so forth were drawn up but as nearly as we can ascertain from media monitoring and contacts, the BICA was never formed. It appears the industry is waiting to ascertain what the current government’s policy priorities might be, as expressed in the outcomes of the current Commission of Audit and Budget, before possibly resurrecting the BICA concept and/or the policy issues identified in the BICC report.” (emphasis added)

My read on this is that the industry won’t take any initiatives itself until it knows what the government might do (i.e., let’s wait to see if there are any handouts, and if not, we can plead a special case about the lack of subsidies/protection and the threat of extinction…).

This defeatist attitude is not just confined to Australia – my former colleague recently attended the 2014 Digital Book World Conference in New York. He commented:

“I was disappointed to see the general negativity of the publishing industry and the “victim” like mentality – also the focus on the arch-enemy – AMAZON! I see great opportunities for content – but companies have to get their head around smaller micro transactions and a freemium model. Big publishers are “holding on” to margins – it’s a recipe for disaster – [but] I think we can become small giants these days.”

There are some signs that the industry is taking the initiative, and even grounds for optimism such as embracing digital distribution in Australia, moving to a direct-to-consumer (“D2C”) model in the USA, and new approaches to copyright and licensing in the UK.

The choice facing the publishing industry is clear: continue to see itself as a victim (leading to a self-fulfilling prophecy of doom and extinction), or become part of the vanguard in developing leading-edge products and services for the digital age.
From EPICS to BISG: Trying to save the Australian publishing industry

At the dawn of the century, the Australian government funded a series of research projects on the future of the local book publishing industry, under the Enhanced Printing Industry Competitiveness Scheme (EPICS). Part of that research effort included the Ad Rem Report on “The Australian Book Industry: Challenges and Opportunities”, published in September 2001.

Scenario Planning

Via consultation with publishers, printers, distributors and book sellers, Ad Rem examined a range of possible scenarios the industry would face leading up to 2010.

Using rather quaint titles for each scenario, from utopian to apocalyptic, the report made a strong case for:

  • increased collaboration and consolidation across printing and supply chain logistics;
  • adoption of new technology (including “print on demand”); and
  • increased focus on adding value through improved customer service.

So, under “Paradise Found”, a loose federation of specialist companies would focus on either printing, publishing or distribution services predicated on increased consumer demand for books and content available from multiple outlets, underpinned by happy customers served by a responsive and proactive publishing industry.

More stoically, selfless cooperation and collaboration in the form of “Shoulder to Shoulder” would ensure that despite reduced demand, the industry could become a “national model of supply chain efficiency” by sharing distribution networks and market data, and adopting industry-wide standards.

Conversely, limited cooperation and the lack of a single, dominant business model would result in a “Dog Eat Dog” scenario, with few local winners. Overall consumer demand would diminish, industry participants would seek to operate all along the supply chain (introducing some market inefficiencies), and the industry would end up competing on price alone, and fighting tooth and nail for the next major “blockbuster” title.

Alternatively, if the “Land of the Giants” was to prevail, “highly diversified global companies from outside traditional media industries would come to dominate the Australian book industry.” Demand would be driven and met by technological changes, carried forward by bundled products and services, end-to-end integrated businesses, and “predominantly proprietary industry standards”.

The reality is, we have “Land of the Giants” (as far as global businesses are concerned), while the local players are fighting it out in a “Dog Eat Dog” world.

Technology

“Print on demand” was going to be the answer, because it would minimise the supply chain logistics, improve sales margins for retailers, and enshrine the protectionism afforded local publishers and distributors under the 30-day rule written into the Copyright Act. In addition, increased training and upskilling would help the industry meet the challenges of digital content and the new means of production and distribution. (The publishing industry has traditionally invested very little into structured training – see Jo Bramble writing in “Developing Knowledge Workers In The Printing And Publishing Industries”, Cope & Freeman (Eds.), University Press/Common Ground Publishing (2002))

However, while ebooks were already on the market in 2001 (mainly read on PDAs), and although online content was already widespread, probably nothing could have prepared the industry for what has happened in the past 10 years such as:

  • the growth of ebook readers such as Kindle, Nook and Kobo,
  • the impact of Apple’s iOS/iTunes/iBook/iPad ecosystem,
  • self-publishing solutions from Amazon to Tablo, or
  • controversial online “library” projects like Google Books.

Print-on-demand never came about, partly because the dot.com boom/bust of 2001-2002 put the dampener on many digital initiatives (remember the original push for “e-Government” in Australia?), partly because internet speeds were not up to scratch, but mainly because there was little or no appetite for industry collaboration and common standards.

Retailing

Infamously, Borders came along to shake up the local market, but ended up laying waste to much of Australia’s book selling industry as it imploded under the weight of expectation (and crippling debt). While a couple of national chains remain, many independent and specialist bookshops have managed to survive – some may even be thriving – as they find ways to develop deeper engagement with their customers, and offer a range of value-added services.

However, sales of books in Australia have maintained a steady (if unspectacular) growth rate); online purchases now account for around 12% of all book sales, of which more than half are generated by overseas websites; meanwhile, ebooks have gone from 1.5% of the local market in 2010 to 10%-12% of all book sales in 2013 (of which 90% are made by offshore retailers).

Geo-blocking

Regular readers of this blog will know I have a thing about geo-blocking* – so, while I am an advocate for intellectual property protections such as copyright, I am against territorial restrictions that prevent/impede customers buying content from wherever/whomever they choose just because content owners and/or their distributors have decided to carve up the market to suit themselves. (Piracy is piracy, but parallel importation is about giving customers choice.)

Amazon finally launched its dedicated store in Australia in late 2013, but only for ebooks, and with an initial focus on Australian authors and publishers. So, for print books, local customers still need to go to the US and UK sites. For whatever reason, Amazon feels it necessary to have a local online presence (to counter protectionism? to avoid arguments over collecting local GST on overseas online purchases? to annoy local retailers who have been selling Kindles?)

What came next? Much the same really…

I can’t help thinking that the combination of an apparent lack of cooperation around standards, reluctance to collaborate on supply chain logistics and an inability to read the technology trends have all contributed to a 2-speed publishing industry in Australia: a series of small, specialist and independent print publishers and bookshops trying to compete with the global digital behemoths of Apple, Amazon and Google.

Despite the considerable effort behind the Ad Rem Report, it’s fair to say that nothing of substance materialised.

Fast forward 10 years, and along came the Book Industry Strategy Group (BISG) which reported in September 2011. Among its 21 recommendations were:

  • consolidation/streamlining within and across the supply chain – to create greater efficiencies
  • adjustments to GST – i.e., abolish/reduce the rate on Australian books, or collect GST on sales under $1,000 by overseas websites
  • increased protection(ism)  – via direct and indirect support for the local industry
  • review copyright legislation – in relation to digital content creation and distribution

Fairly predictable stuff, but not much about technology or related innovation…

NOTES:

The original Ad Rem website was decommissioned some time ago. I do have PDF copies of the various reports and working group papers if anyone if interested – although they are the copyright of Accenture, I’m sure they wouldn’t mind if I distributed a few copies in the interest of research and commentary. Meanwhile, a couple of papers are still online:

Click to access Ad_Rem_Scenario_Planning.pdf

Click to access Ad_-Rem_Value_Chain_Analysis.pdf

*GEO-BLOCKING REFERENCES:

Geo-blocking: the last digital frontier?

Australian MPs recommend a ban on geo-blocking

Amazon finally comes to Australia; local retailers still want government action on sales tax

A short (and seasonal) post this week, as everyone starts easing off for the holidays.

It may just be coincidence, but about the same time Amazon launched their new Australian website local retailers renewed their campaign to lower the $1,000 sales-tax exemption for online purchases from overseas retailers. And both events came at the start of the Christmas shopping season….

Obviously too early to say which way this will go, but here are a few personal observations:

First, the local Amazon site is limited to e-books, games and Android apps. So, no access to music, television or film content (digital or physical), no sales of print books and no Amazon marketplace. For these products and services, customers are directed to the US site. (Previously, the dormant Amazon.com.au domain name referred customers to the UK site.)

[Note: neither the US nor the UK sites allow overseas customers to buy mp3 content, but they can download digital music via Amazon’s AutoRip service when purchasing physical goods – confused? Me too….]

Second, prices for e-books on Amazon’s Australian site appear to be comparable to the US store, and presumably include local sales tax (GST) to keep on-side of the local real world and online retailers (as well as the ATO, of course).

Third, the general consensus is that if the $1,000 threshold was lowered or even abolished, the amount of sales tax to be collected would be more than outweighed by the additional costs of processing, administration and remittance (which would likely be passed on to local consumers at a “cost-plus” rate by overseas online retailers).

Fourth, many local retailers who voice their opposition to the $1,000 tax-free exemption fail to understand some of the reasons why local shoppers prefer to buy from overseas online retailers:

1. Price – even if overseas sales attract the 10% GST, in some cases this would still be cheaper than buying locally (especially so when the A$ was above parity with the US$). For example, from time to time, Amazon’s UK store offers free shipping on physical goods to Australia….

2. Choice – many products available from overseas online stores just aren’t available in Australia. This is primarily due to geo-blocking, confusion over local distribution rights, and simple lack of interest in stocking some items for the local market

3. Service – from recent personal experience, buying from a local online retailer took much longer than buying the same product from an overseas site, because the supply chain logistics were woefully inept.

[Note: As a separate but related example, I recently ordered a new iPhone 5S direct from Apple’s local website, and received it within 3 days, including a weekend; whereas my telco provider – which prides itself on its on-line business model and customer service standards – took more than 2 weeks to send me a new nano SIM card….. I had also been told by a couple of local Apple re-sellers that it would take 3-4 weeks to order the new phone, unless I took out a new mobile plan with them – which may say more about Apple’s trading policies than the resellers’ business operations.]

My advice to local bricks and mortar and even some online retailers is to look at their own limitations before insisting that the government amend the GST-free threshold on overseas online purchases.

As for Amazon, I wish them well in developing their local service. Much has been made of the stated intention to focus on Australian titles, and the opportunity for local authors to self-publish via Amazon. But already there have been some rumblings that this new site may cannibalize Kindle sales made via some of Amazon’s local retail channel partners.

Building a Personal Brand via Social Media – or the AAA Guide to Blogging

I’ve been working with content since I was a teenager – from writing articles for school magazines, to contributing gig reviews to a leading Manchester music magazine; from working for global media and information brands, to freelance editorial and writing projects.

Even now, as a business coach and consultant, I continue to focus on my clients’ content strategies – whether developing new products and services, managing IP, or capturing and commercialising in-house knowledge.

I have to admit to being an early sceptic about Social Media – but I soon recognised its importance, especially when building a personal brand on-line. Now it’s just another communication channel. I sometimes reflect on our ancestors who resisted the telephone, radio and television, and wonder if my own suspicions about Social Media will seem unfounded in retrospect.

About a year ago, I started this blog as a personal brand for my consulting work, as well as giving me a license to write about “Exploring the Information Age”, however tangential it might be to my professional work.*

After 12 months, I think I have found the essence to building a personal brand through social media – otherwise known as the AAA Guide to Blogging. Those elements are: Authenticity, Awareness and Attribution.

Authenticity

In an on-line environment where people hide behind avatars and aliases, you need to find the appropriate level of authenticity if you are going to be taken seriously by or establish trust with your audience. Being authentic means finding your “voice” to express yourself in any given situation, and to be true to yourself in that particular context.

I will admit to having several on-line profiles. For example, when connecting with my family and close friends, I am very circumspect about which Social Media platforms I use, and how I use them. My profile is extremely locked down and tightly controlled – you won’t be able to find me because I won’t let you in.

For my activities as a musician, I have another profile for self-promotion, sales and distribution, community engagement and beta testing new apps. You probably won’t find me because I use an alias, unless I am inviting you in.

Finally, in my professional life, I am very pro-active, interacting via an increasingly interconnected multi-channel strategy.

Does having multiple profiles mean I am being inauthentic? I would say no, because I am being authentic to who I am in those particular situations, and I don’t believe it is unreasonable to keep my private life, my personal interests, and my professional profile separate from one another. That’s why, even though I have a public profile on Facebook as part of my professional brand, I won’t be sharing my musical tastes because it’s not relevant (unless I might be going to a karaoke sessions with my clients?).

Awareness

Just as you need to be aware of the possibilities and limitations of different Social Media tools, you also need to understand your “character” when blogging, sharing and providing status updates. I see this as a natural extension to being authentic – in my professional life, should I really be sharing selfies (especially not at the client karaoke night…)?

There are 4 main categories of Social Media protagonists and bloggers:

1) Enthusiasts – personal stuff, “what I ate for breakfast”, no real purpose
beyond “sharing” or “look at me

2) Broad Experts – know their Yammers from their Spammers, their Blogrolls from their Facebook Trolls – understand how and where they need to engage, they know what works for them (they have found their own level)

3) Niche Specialists – the Twitterati (Stephen Fry), the star fashion bloggers, the political and media pundits, viral cat videos, and the quirky (@God) – NOT Katy Perry – she probably has people to do that for her, namely….

4) Professionals – so-called “prosumers” who use Social Media as part of their job or about their work, or it’s part of their public and personal profile, and the boundaries are increasingly blurred.

Attribution

As far as possible, I always attribute third party content or references I use in my blogs, even if they are deemed to be in the public domain, and I endeavour to acknowledge the original sources as far as possible.

Not only can this create reciprocal links and traffic to my blog, I just believe it is more ethical, rather than “sharing” content with no attribution. It’s not just about copyright law, or respecting IP, I happen to think it is more intellectually honest to acknowledge original ideas, rather than imply they are our own.

I came across a good example recently on LinkedIn, where a connection “shared” an infographic on social media, without providing the original source. In fact, it almost looked as if it was an original post. However, I was sure I had seen the same content elsewhere, and after a short Internet search, I was able to locate the original post and the author very easily. Maybe it’s laziness, or lack of consideration, but this common failure to attribute sources risks undermining your work and devaluing your creativity.

Final thoughts on blogging and Social Media

• No-one gets it right 100% of the time – and even when we do, we don’t always know why
• Conversely, everyone gets it a little bit wrong, so the real learning is in that collective experience
• Prospective employers, clients, customers all expect to find evidence of your Social Media and online presence – even if you are only engaged in Social Media in a professional/work capacity, you still need to develop a personal profile

*See previous blog 10 Rules for Effective Blogging. I recently did some analysis of my blog traffic, to see where my readers are coming from. I don’t use Google Adwords, and I don’t have any paid-for SEO – so I rely on my WordPress stats:

  • Nearly half of all traffic is coming from social networks
  • One third comes from search engines (of which Google accounts for 90%)
  • 10% comes from Reddit

Search results for my blog always come in the top 10 (plus it helps to have an unusual first and last name – always #1 search result!)

Footnote A slightly different version of this article was given as a presentation at the Australian chapter of PR over Coffee earlier this month