The new education #1: Agility

Week 1 of “What they should be teaching at school” – Agility.

We are used to ‘agile’ in terms of project management and software development; it’s even been applied to a style of business management itself. From the agile process, we recognise the value of continuous learning from a combination of task-based collaboration, iterative experimentation, rapid validation and constant improvement.

So it would make sense to deploy agile learning in school. Whether it’s research methods, data validation, practical experiments, rapid testing, team collaboration or scenario planning, agile thinking can foster the ability to be empathetic, consider alternative perspectives,  evaluate different contexts, and respond to new data or situations.

While it’s important to learn core foundational facts and key conceptual frameworks, we can’t remain rigid in the face of new information. But the rate at which our knowledge is changing (new science, new data, new discoveries) also means it’s a challenge trying to keep up. Therefore, agile thinking is essential to being able to gather appropriate information, process and interpret the data, construct and validate innovative theories, and apply them to new situations, based on the available evidence. This approach should also foster greater creativity, build stronger reasoning skills, and see the development of logical thought processes.

Next week: Resilience


What they should teach at school

Content in Context is currently on the road – so this week’s blog is a holding post pending resumption of normal service next week. The theme for the next three entries will address what schools should be teaching, in addition to the 3Rs (4 or 5 if you include reasoning and rationality) – namely: Agility; Resilience; and Curiosity.

Next week: Agility

The Future of Super

As I mentioned in last week’s blog on the recent Intersekt conference, there was an interesting panel discussion on Superannuation – interesting not just because of the topic, but also because it was about the only session I attended at the conference where there was some real disagreement among the speakers. Just goes to show how sensitive and contentious Super has become – and this was not even a discussion about the Royal Commission!

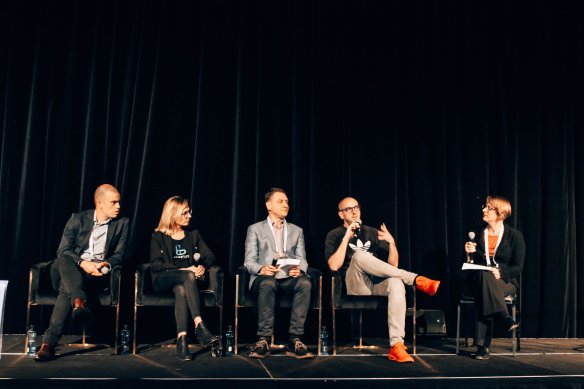
L to R: Peter Stanhope, Carla Harris, Greg Einfeld, Jon Holloway. Moderator Erin Taylor. (Photo sourced from Facebook)

The protagonists were Jon Holloway (Zuper), Carla Harris (Longevity App), Peter Stanhope (GIG Super) and Greg Einfeld (Plenty Wealth).

With around $2.7tn in assets under management, we were told that the Australian model for state-sponsored, privately funded retirement planning is the envy of the world. Yet we also heard that it has been so badly executed at home that we are in the midst of a huge shift in our attitudes towards this defined contribution scheme. And this is not just about disruption or technology – there are serious concerns that many Australians are not willing and/or able to set aside enough assets to provide for their retirement living; that the system is being rorted via skewed tax rules, gender-based wage disparity and expensive management fees; and that there is an overall lack of investor education, interest and engagement.

But for context, and in Super’s defence, the system has helped to make Australians a lot wealthier (along with property), and rank higher than Switzerland for median wealth. And as The Economist recently reported, for good or for bad, Super means that Australia does not have as heavy a state pension cost as most of the OECD.

Some of the issues facing the industry, as outlined by the panel include:

  • the changing definition of “ordinary Australians” (who are they? how is this even defined?)
  • the changing nature of work (the gig economy etc.)
  • the need for Open Super Data (to make choice and switching easier)
  • redefining “retirement” (given we are living longer beyond the traditional working age)
  • addressing gender imbalance in wages and contributions
  • redundant marketing imagery used by much of the Super industry
  • why the audience is under-educated and under-engaged on this topic
  • too little industry competition (although the regulator APRA is known to favour consolidation of smaller funds which are not sustainable)
  • the advice delivery channel needs to change, as does access to, and choice of, products and providers
  • the technical infrastructure is not fit for purpose for things like custody and administration (still living in the 80s?)
  • tax planning (a key rationale for how super is managed is determined by tax minimization)
  • generational change (linked to changing work patterns)

The panel discussion was followed by a fireside chat between Kerr Neilson of Platinum Asset Management, and Simon Cant of Reinventure. According to Mr Neilson, the key structural changes facing the industry are a direct result of financial planning advice becoming less profitable: no more trailing commissions (probably a good thing?); fewer advisors in the market (due to increased professional education requirements) with a resulting shift to accountants; and even robo-advice is not truly scalable. Meanwhile, for anyone watching their Super balance and returns, beware the Trump knock-on effects of trade tariffs and interest rates – this will require greater asset diversification, and robust currency risk management, to take advantage of new investment opportunities.

Next week: What they should teach at school

Intersekt Festival 2018

This year’s Intersekt Festival, held in Melbourne last month, was put together in quite challenging circumstances, given some of the recent events within key industry body FinTech Australia, the primary event host. It was a credit to all involved.
Not surprisingly, given some of the regulatory and industry changes underway in Australia, the key themes included: Open Banking and access to data: Trust in the banking and financial services sector (thanks to the Royal Commission, and the APRA report on the CBA); Data Privacy; Payments and the NPP; Comprehensive Credit Reporting and predatory lending practices; and Equity Crowdfunding. And of course, a little bit about Blockchain, Cryptocurrencies and Security Tokens.

There was a lot of discussion on “Trust”, especially in the age of Uber and Airbnb – how have these marketplaces managed to earn so much public and consumer trust in such a relatively short time? Yet as consumers, we obsess about Open Banking vs Data Privacy,  while banks themselves appear to be more infatuated with their Net Promoter Score…. whereas “Trust” is clearly a huge issue. In the case of the banks and the fall out from the Royal Commission, there was a discussion about whether our key financial institutions have come close to losing their social license to operate.

Meanwhile, with the prospect of self-sovereign digital identity becoming a practical reality (fuelled by blockchain, decentralisation and trust-less protocols and standards), there is a demand for cross-functional  (and cross-border) solutions for KYC/AML processing and identity management. But a lack of mutual regulatory recognition or harmonization (as opposed to “mere” industry standards) plus a diversity of business models confounds regulatory harmony, often within a single jurisdiction, let alone across multiple markets.

When it comes to payments and the NPP, it’s clear that regulation lags technology. For example, despite the existence of a (complex and somewhat uncertain) licensing regime for purchased payment facilities, APRA has only licensed one such PPF – PayPal. As former ASIC Chairman, Greg Medcraft once observed, by the time the NPP is fully operational, Blockchain will have gotten there long beforehand. And given the preponderance of stored value cards, digital wallets, peer-to-peer crypto exchanges, and multiple overseas and cross-border mobile payment apps, the respective regulatory roles of RBA, APRA, AUSTRAC, ATO and ASIC need to be clearly defined and set out.

On the topic of data protection and “big data”, there was a lot of discussion about getting the balance right between privacy and innovation. One the one hand, industry incumbents should not be allowed to use their market dominance to resist open banking and stifle the emergence of neo-banks; but on the other, there is a need to shelter the forthcoming consumer data right (CDR) from potential abuse like predatory lending (e.g., not simply define the CDR standards by reference to existing banking products and services) – mainly because the CDR is designed to empower consumers (not embolden the industry), and it is designed to be sector neutral (i.e., equally applicable to utilities, ISPs, telcos, insurance firms).

Other topics included SME lending, where new, tech-driven providers are not only originating new loans, but also refinancing existing businesses as the big 4 banks are seen to withdraw from this market; home loans (where technology is driving new loan origination, funding and distribution models); social impact (“FinTech for good”); equity crowdfunding (and the role of STOs); insurance (creating a decentralised market place) and Superannuation (which prompted perhaps the most contentious panel discussion – more on that to come!).

If there were any criticisms of the conference, based on local and overseas delegates I spoke to, they related to the length (was there enough content to sustain nearly 3 days?); the need for clearer roles and participation by the major and regional banks; the absence of investors (despite a speed-dating matching event….); and a desire to see a broader range of speakers and panelists (too many of the “usual suspects”?).

Next week: The Future of Super