Australian MPs recommend a ban on geo-blocking

In a recent blog about geo-blocking, I commented on the frustrations of Australian consumers in trying to access digital content. That blog was written in light of a parliamentary inquiry into IT price discrimination.
ImageA Report by the House of Representatives Infrastructure and Communications Committee has just been published, and makes for some fascinating reading.

The Report reveals a number of key themes:

  • There is strong evidence that Australian consumers pay between 50 and 100 per cent more for the same product than consumers in comparable markets.
  • Price differentials cannot be fully explained by the so-called “Australia tax” (i.e., the relatively higher costs of doing business locally, due to wages, taxes, market regulation, shipping costs, economies of scale, etc.).
  • Consumer complaints about price discrimination are not being taken seriously by the industry as a whole.
  • Industry participants either deflected responsibility for price discrimination to other parts of the supply chain, or blamed inconsistent market practices as justifying the need for different regional and national price policies.
  • Despite being given the opportunity by the Committee to defend their pricing practices in public, most industry participants declined to co-operate in full; this gave rise to Apple, Adobe and Microsoft each being compelled to give evidence.
  • A number of submissions made by industry participants appeared to be disingenuous, self-serving, evasive and even misleading.

The Committee accepts that IT vendors are entitled to run their businesses as they see fit, and there is nothing to stop them from charging whatever prices they like. There was also general acknowledgment that copyright holders must be able to protect their IP assets.

However, geo-blocking (especially of digital content) simply reinforces price disparity based on a customer’s geographical location, rather than protecting the interests of copyright holders. Further, although so-called “Technological Protection Measures” (TPM) or “Effective Technological Measures” (ETM) and “Digital Rights Management” systems (DRM) may have a legitimate role in controlling copyright (and as such they enjoy protection under the relevant Copyright Law), their net effect has been to limit competition and to lock consumers into “walled gardens” which places considerable power in the hands of IT vendors as to how, when and where consumers access content.

In short, the Committee made several recommendations designed to address price discrimination and restricted market access imposed on Australian consumers, including:

  • Remove any remaining restrictions on parallel imports (in a bid to increase market competition among distributors and retailers).
  • Clarify the legal circumvention of TPM/ETM/DRM barriers that are purely designed as geo-blocking tools (rather than copyright protection measures).
  • Educate Australian consumers about their ability to buy cheaper goods from overseas, or to legally circumvent geo-blocking (without compromising product warranties or infringing copyright).
  • As a last resort, place a ban on geo-blocking and outlaw contacts or terms of service that rely on and enforce geo-blocking.

Unfortunately, while this Report is of great significance to the Australian digital economy, and seeks to achieve a balance between the rights of copyright holders and the interests of consumers, it is likely to be overshadowed by concerns about tax avoidance in respect to multinational companies. No doubt Australian consumers will make a connection between global IT companies whose products they buy, and transnational tax minimization strategies linked to transfer pricing policies and the routing of content royalties and copyright licensing fees via low-tax jurisdictions.
Has digital killed the music industry?

Or, more specifically, has disintermediation broken the business model?

Image

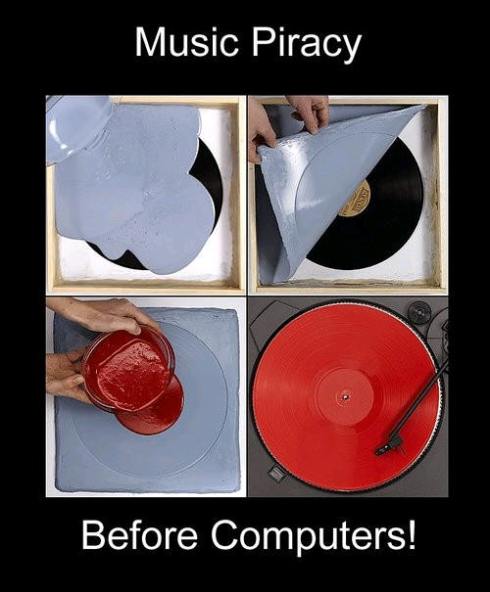
Ever since the invention of compact cassettes in the 1960s and the arrival of the Walkman in the 1970s, pundits have been predicting the end of the music business (remember those “Home Taping Is Killing Music” campaign logos of the 1980s?) – a theory that look set to come true in the 1990s with the launch of mp3 players and peer-to-peer file sharing. Yet, rather like Mark Twain, the death of the record industry appears to be greatly exaggerated.

Most debate about the demise of the music industry is predicated on the impact of technology that facilitates music piracy, whereas in reality the business model has been broken as a consequence of digital disintermediation.

For most of its history, the recording industry was a model of vertical integration. The major record labels owned the content, the means of production (recording and manufacture), the publishing and licensing activities, the distribution channels – and in some cases, they even manufactured the hardware, owned the retail stores and promoted live concerts.

The 1970s began a rapid process of horizontal integration, as the major record labels merged with one another at such a rate that by the late 1990s there were really only four global companies – Sony, Warner, Universal and EMI. At various times, each of these companies has also been affiliated to substantial film, electronics and publishing interests – further proof of the vertical and horizontal integration.

The “Big Four” have now been reduced to just three with the sale of EMI to Universal. European Union Competition rules resulted in parts of the EMI group of labels being divested to Warner, and the music publishing division being sold to Sony/ATV Music Publishing.

EMI was probably the epitome of vertical integration – but over the years, it was forced to sell or close assets like its UK manufacturing plant and the HMV retail chain, and came close to selling off London’s Abbey Road Studios (a decision that was reversed following public outcry and reinforced by a heritage listing). Some observers blame poor business decisions and weak digital strategies for EMI’s demise, but I would argue that the highly integrated model has been found wanting, and EMI was a dinosaur that could no longer survive in its current form. For example, despite some errors of judgement (such as putting “Copy Control” software on their CD’s which affected their ability to play on personal computers), in many ways EMI was something of a pioneer in digital music – being one of the first major labels to remove DRM from its downloads, and licensing its content for streaming services.

Despite the rampant corporate contraction, the growth of digital download platforms and the expansion of music streaming services, it’s clear that record labels still have a role to play in developing and distributing new content. Independent labels, distributors and retailers continue to wax and wane according to the fortunes of the wider industry, and technology makes it even easier for artists to self-release their recordings direct to the customer – but record labels provide the financial and marketing support that are critical to commercial success, and other intermediaries (publishers, distributors, licensees, retailers, promoters, etc.) continue to add value to the supply chain.

In fact, just this week, Billboard has been running a poll on whether Universal and Sony should break away from their parent entertainment conglomerates – the theory being that the music labels represent greater value on their own, especially when unencumbered by ailing electronics and movie businesses. Results so far suggest that ownership does not matter so much as having the best strategies for, and access to, the means of content creation and distribution.

At the same time, the music industry is going through another round of vertical and horizontal integration and disintermediation, driven by new technology, new distribution platforms and new business models linked to the way we access and consume content. So, while Apple’s iTunes platform has been accused of anti-competitive practices in its dealings with content owners, it also faces competition from music streaming services like Spotify, Rdio and Pandora, and new content platforms like Twitter’s #music and Vine. And if sales of new CD’s (and even mp3 downloads) are reportedly declining, there is still healthy demand for live music events especially those linked to the marketing of established back catalogue titles, which is where record labels come into their own as curators of re-released and re-packaged content.

In conclusion, here are some random reasons why I think the music industry is actually in good health:

Publishing is Dead – Long Live Publishing!

The name of this blog was inspired by a former colleague at The Thomson Corporation. As our team embarked on a major push into digital media in the mid-90s, he reminded us that the old publishing mantra “Content is King!” was being recast as “Content in Context”. Simply having loads of content was no longer enough to command a dominant or exclusive market position – publishers had to make sure their content was timely, relevant and easy to navigate. Ultimately, content has to help users find insights to their problems and solutions to their needs quickly and efficiently.

I was reminded of this recently when I heard some data storage experts talking about the challenges of what to do with all the data we are creating – especially at the rate we are going. According to latest analysis, 90% of all data was created in the last 2 years.

We keep being told that publishing is dead, but it is clear that we are producing more content than ever before – in which case, it’s great to be part of a dying industry! Sure, the business models are changing, and so is the technology; but there are still a number of core publishing disciplines that we risk losing sight of as we continue to develop boundless and limitless volumes of digital content.

There are several skills that publishers traditionally bring to any new content, print or on-line. And it’s not just about technology, SEO or the number of “Likes”. Any content owner seeking to engage vendors to develop their digital assets and manage their on-line presence would be well advised to ask potential suppliers about their experience, strengths and processes in each of the following areas:

  • Commissioning – having a nose for new authors, where to find them and how to nurture their talent
  • Editing – turning text and data into meaningful and coherent content, including length, structure, tone, clarity and access (tables of contents, indexing, cross-referencing, citations, footnotes, bibliographies, etc.)
  • Design – using appropriate formats, layout and fonts to suit the material and the readership
  • Customer Engagement – bringing the audience into the publishing process, through market research, pre-sales activity and user groups
  • Marketing – knowing how to distribute particular content or promote a particular writer
  • Content Management – analysing the usage data and capturing audience feedback, to understand the value of the publishing assets

Yes, these skills do exist in the digital realm, but increasingly the publishing process is being made subservient to the technology, often at the expense of meaning and comprehension. Doubtless this stems from the misconception that the speed and frequency of publication renders everything as mere ephemera – so why do we need to bother with such archaic ideas as an index?

An author acquaintance of mine recently lamented the response of his publishers who, when informed that his text-book needed an index before it could be distributed in schools, responded, “what a great idea – why don’t you send us one!” I can only assume that the publishers were so caught up in on-line media that they had forgotten how most readers navigate books or other content, especially when they are accessing them for the first time.

On-line developers do us a great disservice if they forget that digital content needs tools such as indexes and tables of content to aid user navigation and accessibility – text tagging and search functions are all very well, but they do not always return relevant or meaningful results, and they can create unintended or unforeseen linkages that may be completely out of context.

As a consequence of the exponential growth in on-line content, and our simultaneous interest for archive material (and the demand for data analytics), publishers are increasingly taking on a new and important role as curators – managing content assets, understanding how to present them, knowing the value of the material they are dealing with, and finding the right context in which to provide this content.

This shifting role of publishers is just confirmation that publishing is far from extinct.

6 Melbourne Start-Ups to Watch…

LogoRecently, I blogged about Audiobus, and the success of its collaborative approach to app development. So last week, I attended a very entertaining “pitch’n’pizza” evening for start-ups, to see what other interesting things are going on in app and content development. The event was organised by Lean Startup Melbourne and hosted by inspire9. Other support came from BlueChilli, General Assembly, Startup Leadership, PlayFi and Kussowski Brothers.

The idea was a mix of Open Mic Night, and “Dragons’ Den” – 6 start-ups presented their pitch to a panel of VC’s and angel investors, in front of an audience of 300+ friends, colleagues, hangers-on and curious onlookers all fuelled by free beer and pizza.

Melbourne is something of a “Silicon Laneway” – not quite a valley, but more of an alley, given the city’s landscape of back streets and converted warehouses that are fostering a culture of start-ups, digital creatives and social media entrepreneurs.

On the night, the 6 hopefuls that presented were:

  • Tablo – a self-publishing platform for authors – sort of Bandcamp for books, but with even better content distribution
  • PetHomeStay – an on-line booking system for pet owners who want to leave their animals with a trusted pet lover while they are on holiday
  • CareMonkey – an app that shares childrens’ health care needs with relatives, schools and sporting clubs, so that teachers, coaches and carers have relevant support information at their fingertips
  • CoinJar – a platform that enables consumers and merchants to transact with Bitcoin
  • Fairshare – an app designed to take the hassle out of shared living (but not to be confused with FairShare….?)
  • SwatchMate – a combined app and smart phone device for matching colours, primarily for painting and decorating

Each presentation was of a very high quality, although some were more polished and rehearsed than others, and only a couple really shone through in terms of having both a great idea and a great commercial offering.

The questions asked by the panel of experts provided some helpful insights on what makes a successful or engaging pitch:

  1. Why? Having a personal experience resonates, and can avoid the awkward “is this a solution in search of a problem?”
  2. Competitors? What makes you different – smarter? cheaper? quicker? Are you truly disruptive or innovative? Or have you just designed a better mousetrap?
  3. Commercialisation? Show me the money! What’s the business model? Where is the revenue coming from? (“Simple is not always best, but best is always simple”)
  4. Customers vs Users? If the paying customer is actually different to the end-user, then make sure this is clear and you have a strategy to connect the dots and to monetize the key part of the transaction
  5. Real world vs On-line? Are you replicating something which already happens in the real world? Can real world transactions easily dis-intermediate your on-line business model?
  6. App or Website? Is it a dedicated app, or is it a website that works well on mobile devices? Going for a well-designed website may be cheaper, and lead to greater/faster customer adoption.

And in keeping with the spirit of this blog, I would add that the essence of all of these new businesses is having interesting content and a meaningful way for people to engage and transact with it.

At the end of the presentations, the panel selected their favourite pitch (the winner getting the chance of a meeting with the VC of their choice), while the audience voted for the people’s choice. Not surprisingly, the panel went with CoinJar, while the people went for Tablo (which also got my vote).

Disclosure: The author does not have any connection to or commercial relationship with the presenters or sponsors mentioned in this blog. He didn’t even get there in time for a free slice of pizza or bottle of beer.